
News & AnalysisCareer

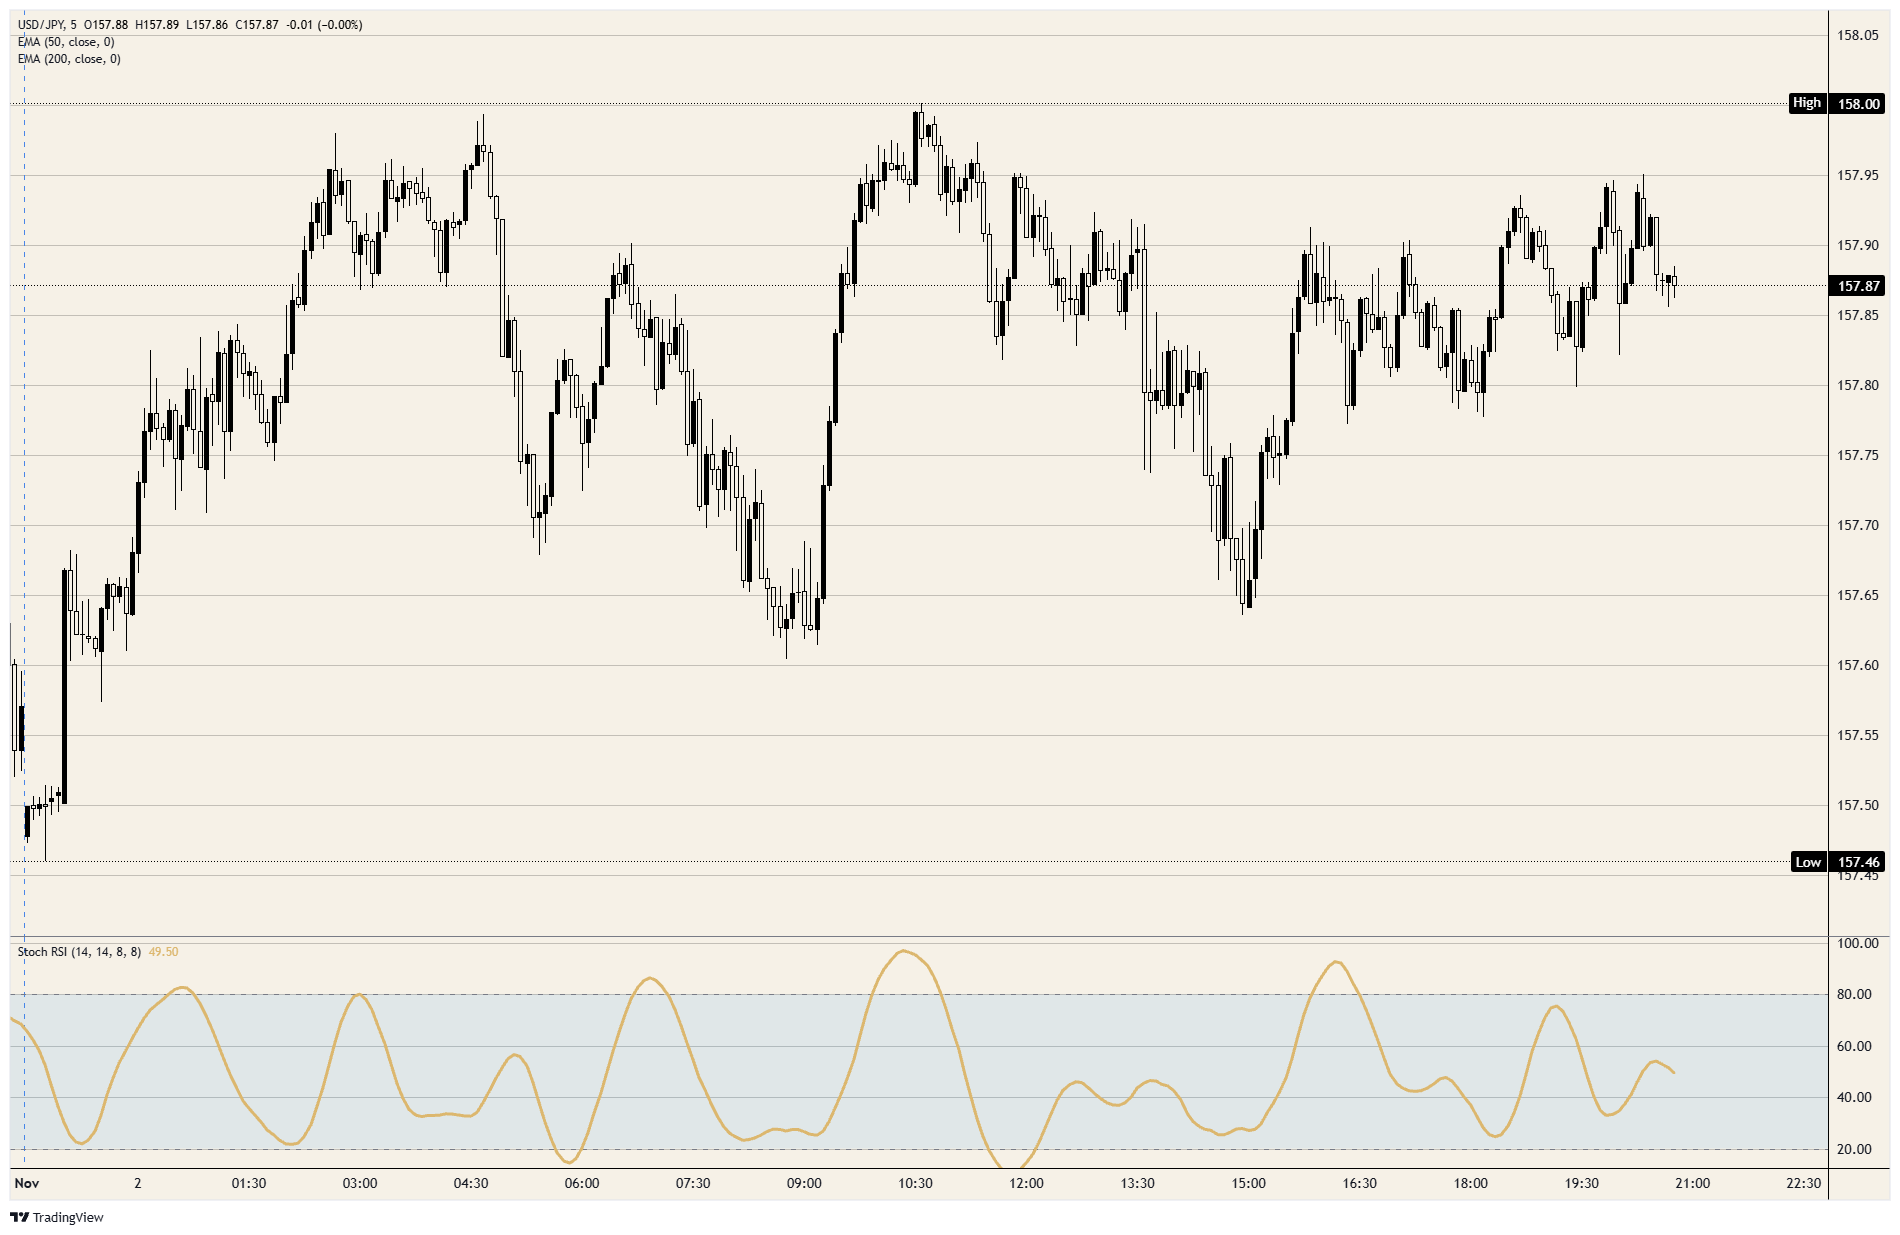
A move to 158.00 took USD/JPY to its highest level since 29 October, even as US-Iran diplomacy weighed on the dollar against the euro and the pound. The yen did not share in those gains against the dollar. When the dollar’s losses elsewhere were deepest, the pair briefly retreated to just above 157.50 before recovering to its high. It now trades a little below 158.00.
With almost all of Japan’s crude oil purchased overseas, the fall in oil prices prompted by US-Iran talks reduces the country’s import costs. Nevertheless, the yen weakened. The next Bank of Japan (BoJ) decision is not due until 17–18 December, leaving no scheduled change to the Japanese side of USD/JPY’s interest-rate differential for more than six weeks.
A decline in S&P Global’s final US manufacturing index, from 56.0 to 54.9, saw USD/JPY ease to just above 157.50. The subsequent Institute for Supply Management (ISM) manufacturing survey climbed to 55.5, exceeding the 54.6 forecast, and the pair recovered to a little below 158.00.
Due on Wednesday at 23:50 GMT, the BoJ’s meeting minutes come ahead of September wage figures at 23:30 GMT on Thursday. Annual wage growth is forecast at 3.8% for a second consecutive month. On Friday at 16:00 GMT, BoJ Governor Ueda is scheduled to deliver a lecture at the International Monetary Fund (IMF). All three will inform the BoJ’s December decision.
Following the Fed’s decision to keep rates at 3.75%-4.00% on 28 October, two US releases will bear on USD/JPY’s interest-rate differential. Wednesday’s ISM services index is due at 15:00 GMT, with a reading of 54.8 forecast after 54.9. Friday’s October payrolls report follows at 13:30 GMT, with 65K expected after 29K.
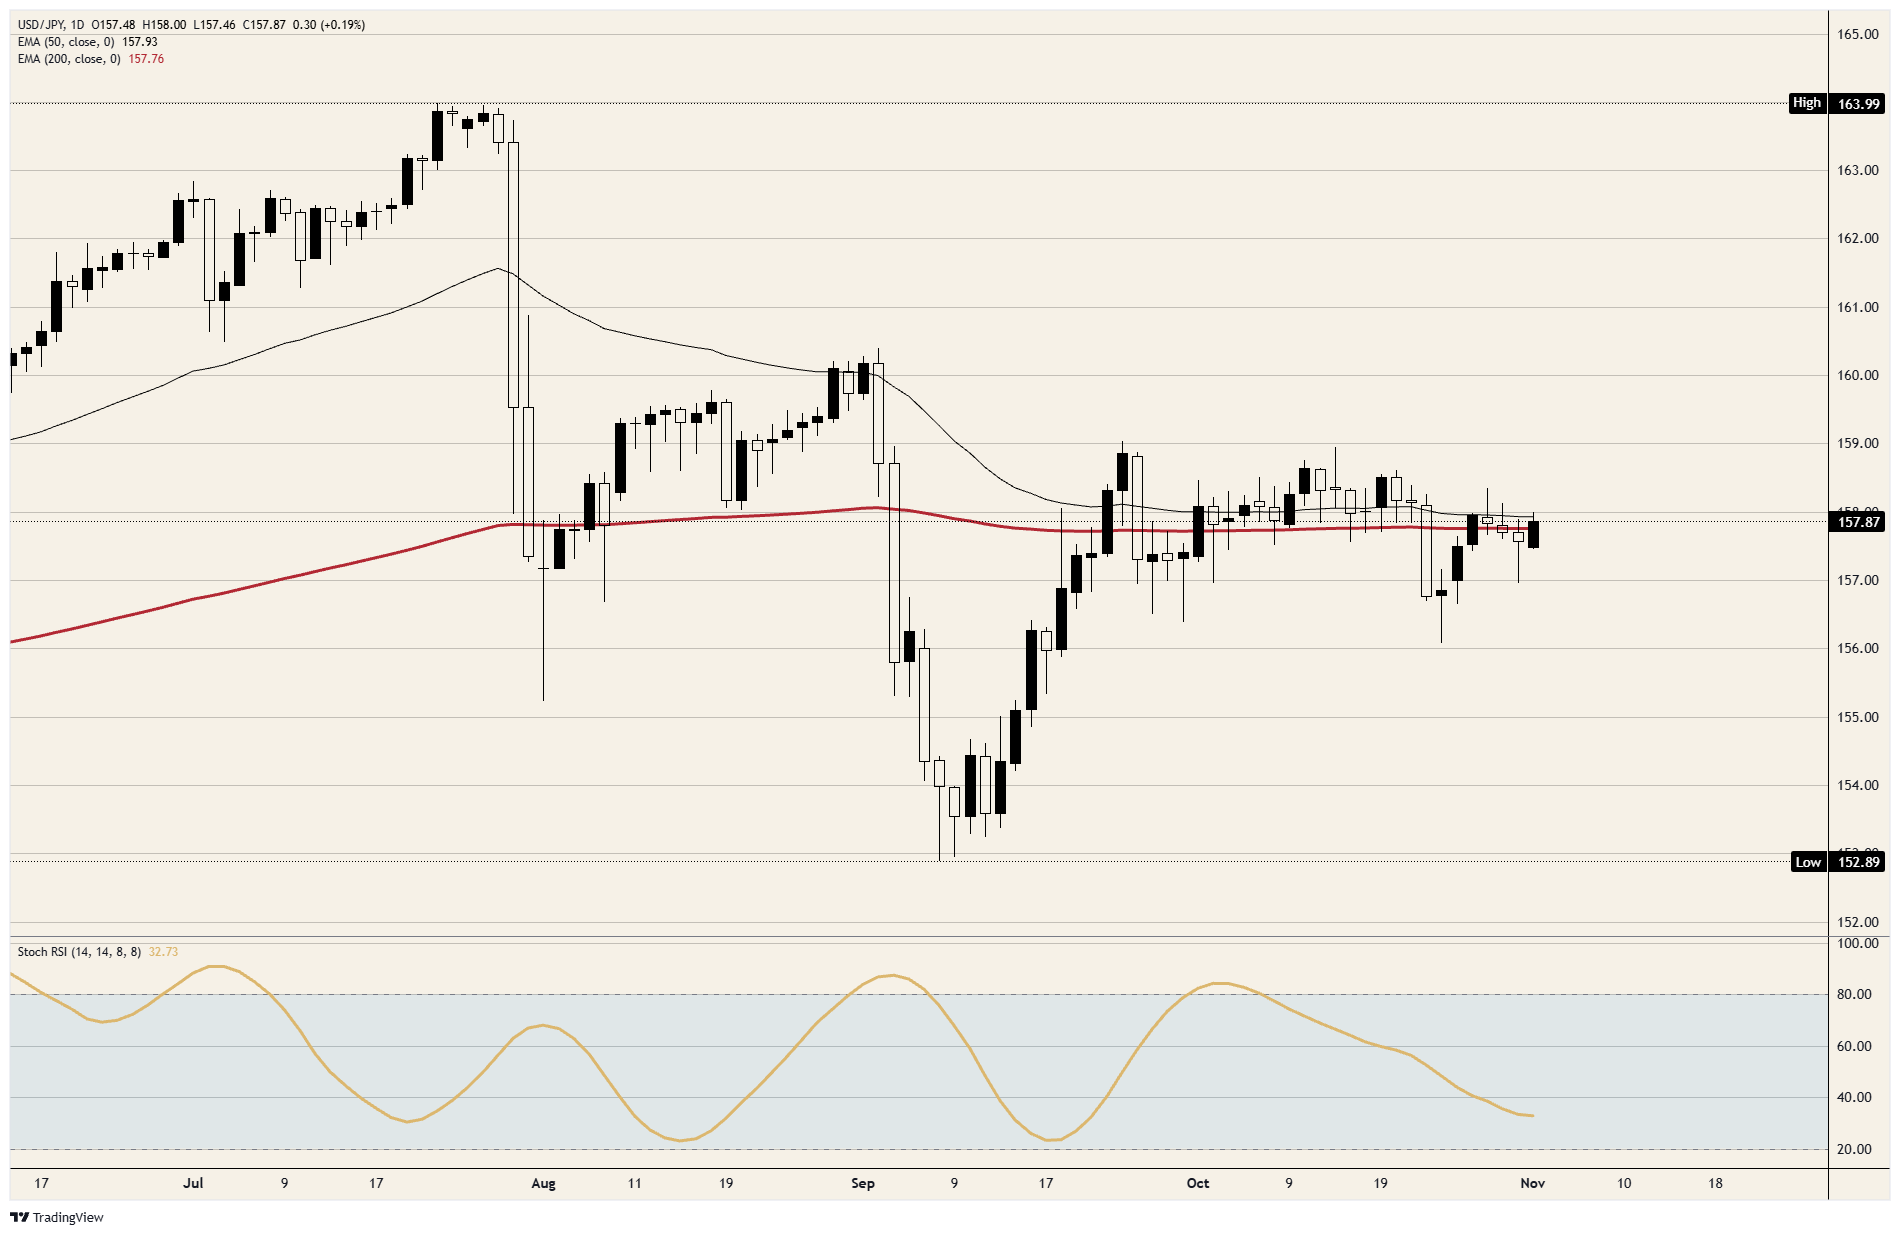
Following a recovery from September’s low just below 153.00, USD/JPY has traded between a little above 156.00 and close to 159.00 since late September. Within that range, the 50-day and 200-day exponential moving averages (EMA) sit less than a fifth of a yen apart. Since early October, the pair has moved across both averages on repeated occasions.
Among the most actively traded currencies worldwide, the Japanese yen (JPY) takes its broad direction from Japan’s economic performance. More specific influences include Bank of Japan policy, the gap between Japanese and US bond yields and traders’ appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan’s mandate, making its actions an important influence on the yen. Direct intervention in currency markets has occasionally been used by the BoJ, usually to weaken the currency. Such action remains infrequent, however, because of political concerns among Japan’s main trading partners. Between 2013 and 2024, an increasing divergence between the BoJ’s ultra-loose monetary policy and the policies of other major central banks drove the yen lower against its principal currency peers. More recently, the gradual withdrawal of that exceptionally loose policy has provided the yen with some support.
By maintaining ultra-loose monetary policy over the past decade, the BoJ increasingly diverged from other central banks, notably the US Federal Reserve. That divergence helped widen the yield gap between 10-year US and Japanese bonds, favouring the US dollar over the Japanese yen. The differential is now narrowing as the BoJ gradually moves away from ultra-loose policy, following its 2024 decision, while other major central banks cut interest rates.
Often regarded as a safe-haven investment, the Japanese yen tends to attract investors during periods of market stress because of its perceived reliability and stability. As a result, turbulent conditions are likely to lift the yen against currencies considered riskier investments.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


