
News & AnalysisCareer

A modest rebound in October employment is anticipated after September's sharp fall, with Statistics Canada due to publish its Labour Force Survey on Friday at 13:30 GMT. Markets will also scrutinise the unemployment rate, as the figures could affect the Canadian Dollar (CAD). Uncertainty over United States (US) tariffs continues to cloud the Canadian labour market, weighing on recruitment prospects in trade-sensitive industries. Having seen the economy lose nearly 110K jobs across August and September, investors will be looking closely for evidence that employment conditions are stabilising.
According to Royal Bank of Canada (RBC), public-sector roles, notably in education and healthcare, accounted for much of September's employment fall, rather than industries with direct exposure to US tariffs. The bank also points to tentative signs of stronger hiring demand in October. These suggest that trade restrictions may have interrupted the labour market's recovery without causing a more widespread deterioration.
The Bank of Canada's (BoC) benchmark interest rate rise on 28 October, its first in more than three years, lends added significance to the employment data. Further monetary tightening remains an option for the central bank, but subsequent decisions will be guided by incoming figures on economic growth and inflation.
In this context, employment figures that exceed forecasts could strengthen expectations of additional BoC interest rate rises, especially alongside resilient wage growth. A further weak report, by contrast, could prompt concerns over Canada's capacity to weather persistent trade tensions and lead policymakers towards a more cautious stance.
An unchanged October unemployment rate of 6.5% is the consensus forecast among analysts for Canada. They also anticipate a gain of around 13.6K jobs, which would reverse part of September's sizeable 68.3K fall.
A slightly larger gain of 15K jobs is forecast by RBC, alongside a small drop in the unemployment rate to 6.4%. In the bank's view, US tariffs continue to affect directly exposed sectors most heavily. It notes that more than 80% of Canadian exports to the US still enjoy duty-free access under the United States-Mexico-Canada Agreement (USMCA).
To judge whether Canada's labour market is beginning to stabilise, investors will look beyond the headline numbers. Manufacturing employment, full-time jobs, wage growth and the participation rate will receive particular scrutiny.
Friday at 13:30 GMT brings the release of Statistics Canada's October employment figures. Should the report beat expectations, the Canadian Dollar could find support, especially if unemployment falls and wage growth strengthens. Such a combination would bolster expectations of further monetary tightening by the BoC.
A further disappointing jobs report, however, could lower expectations of additional interest rate rises and put pressure on the Loonie. That risk would be particularly relevant if job losses spread beyond industries directly exposed to US trade restrictions.
With the US employment figures due at the same time, USD/CAD could also see greater volatility. Investors will weigh the comparative strength of the two labour markets and what it means for monetary policy.
A stronger US Dollar (USD) is underpinning a positive trading bias in USD/CAD around 1.4070 on Friday. Market sentiment remains cautious ahead of the employment releases from both countries.
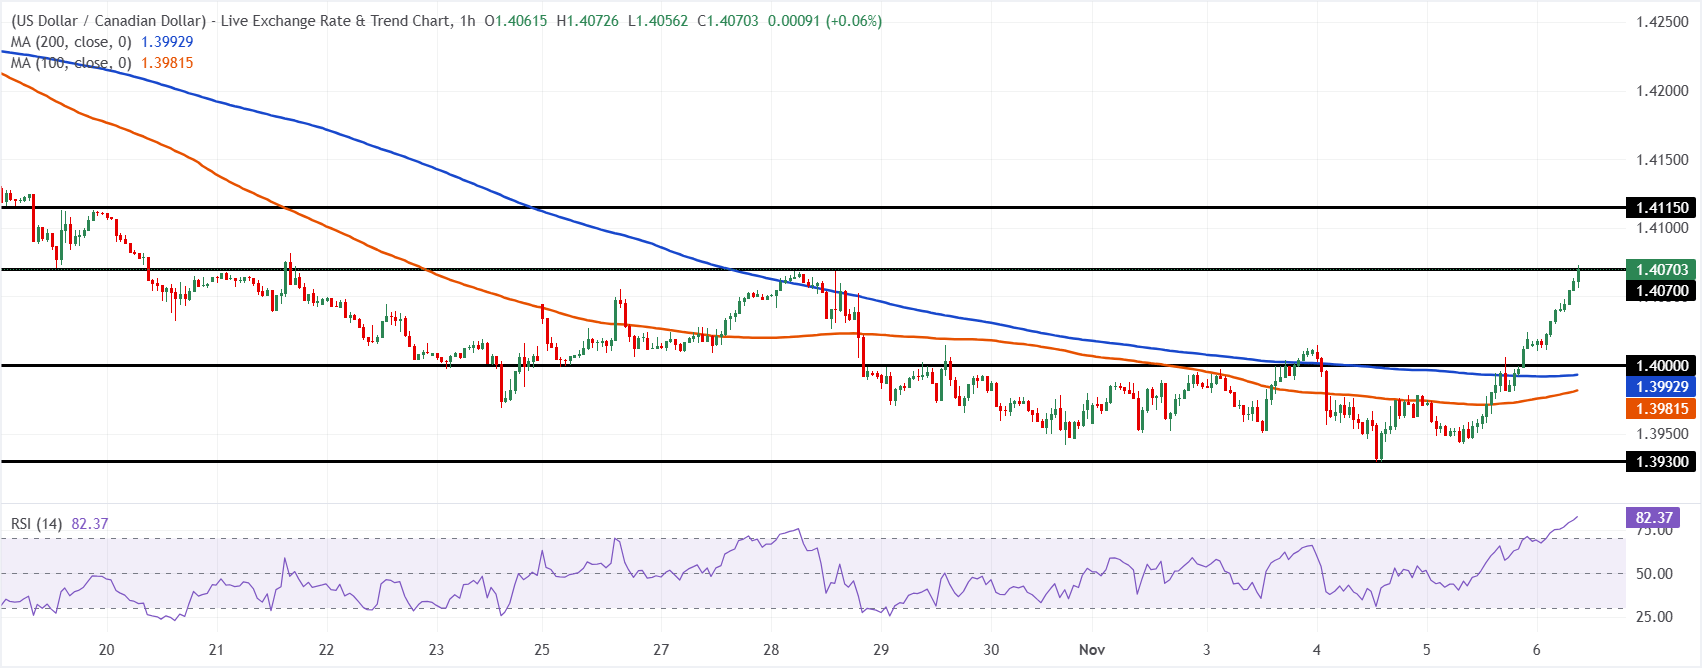
Trading above the 100-period and 200-period Simple Moving Averages (SMAs), which converge just below 1.4000, USD/CAD retains a constructive short-term bias on the one-hour chart. The pair is testing horizontal pivot resistance at 1.4070. Meanwhile, the Relative Strength Index (14) sits deep in overbought territory near 82, suggesting that upward momentum remains strong but is becoming increasingly stretched as the pair advances.
A decisive break through 1.4070 would bring the immediate resistance at 1.4115 into view. This horizontal barrier could limit further advances if buyers cannot sustain the breakout. Should the pair retreat, initial support lies at the psychological 1.4000 level, ahead of the 200-period SMA near 1.3993. Further down, the 100-period SMA around 1.3981 and horizontal support at 1.3930 form a deeper demand zone in the event of a corrective pullback.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Published by Statistics Canada, the Net Change in Employment measures how the number of people employed in Canada has changed. An increase generally signals economic growth and has positive implications for consumer spending. A high reading is therefore regarded as bullish for the Canadian Dollar (CAD), whereas a low reading is viewed as bearish.
Continue reading.Upcoming release: Fri 6 Nov 2026 13:30
Publication frequency: Monthly
Consensus forecast: 13.6K
Previous reading: -68.3K
Data source: Statistics Canada
Among Canada’s labour market statistics, the Employment Change figure carries the greatest weight for the Canadian dollar, which is often significantly affected by these releases. The number of people in work is closely correlated with consumption. This, in turn, influences inflation and the Bank of Canada’s interest rate decisions, moving the C$. When actual readings exceed consensus forecasts, the outcome tends to be bullish for CAD, with currency markets generally responding to the release in a steady and consistent manner.
As an important measure of economic health, labour market conditions play a central role in currency valuations. When employment is high, or unemployment low, consumer spending and economic growth benefit, supporting the domestic currency. A particularly tight labour market, in which there are too few workers to fill vacancies, can also affect inflation and, consequently, monetary policy. When demand for workers is high but labour supply is limited, wages rise.
For policymakers, the rate of wage growth across an economy is a crucial consideration. Rapid pay increases give households more money to spend, typically pushing up consumer goods prices. Unlike more volatile inflation drivers, such as energy prices, wage growth is regarded as a core source of underlying, persistent inflation because pay rises are unlikely to be reversed. This is why central banks worldwide closely monitor wage data when setting monetary policy.
A central bank’s objectives determine how much emphasis it places on labour market conditions. For some, the mandate explicitly extends beyond controlling inflation to include labour market goals. Promoting maximum employment and stable prices, for instance, forms the dual mandate of the US Federal Reserve (Fed). By contrast, the European Central Bank’s (ECB) sole mandate is to keep inflation in check. Whatever their mandates, however, policymakers regard labour market conditions as an important consideration because they indicate the health of the economy and are directly linked to inflation.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved

