

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Data-centre backlash wipes out Dow Jones Industrial Average’s midterm rally
- DJIA hits its lowest since October 14. A backlash against data centres wipes out Wednesday's rally.
- About a third of the points lost comes from Goldman Sachs and Caterpillar, versus about 6% from Nvidia.
- 65K is the October payrolls forecast, up from September's 29K; the report arrives Friday at 13:30 GMT.
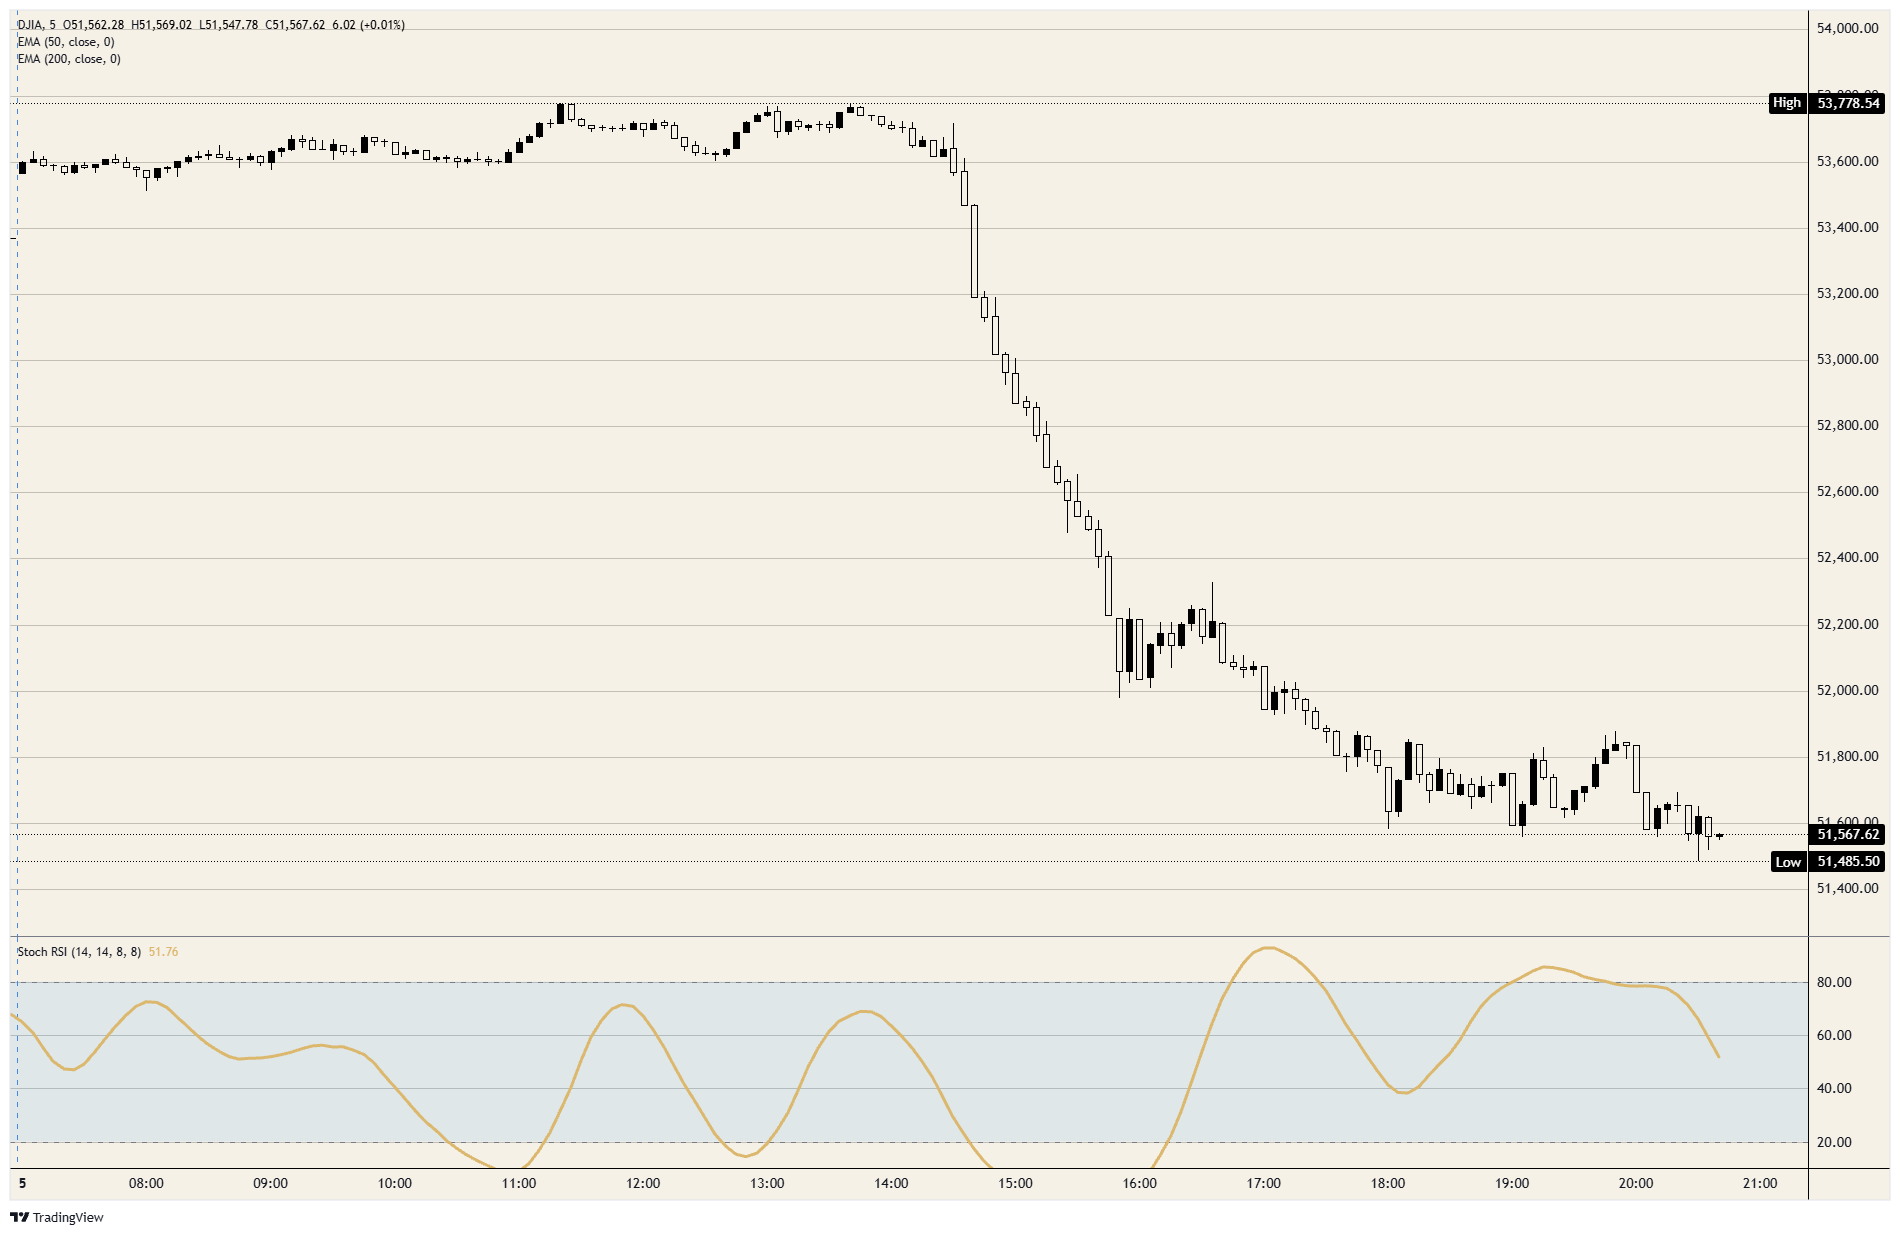
The Dow Jones Industrial Average trades just above 51,500. That leaves it below Tuesday's close and at its weakest since October 14. After recording its best session since April 2025 on Wednesday, the index is heading for its worst since that same month on Thursday, with both moves driven by the same election result. Of its thirty constituents, twenty-nine are falling. Coca-Cola (KO) is the exception.
A sell-off that began in chipmakers has spread across the market. Chip stocks collectively are heading for their worst session since March 2020, while the Nasdaq Composite stands more than 10% below its October record. The Cboe Volatility Index (VIX) reached 28, a level last seen on March 31. Tuesday's result is being read by investors as a verdict on data-centre expansion. Compared with the other two indices, the Dow has less exposure to that trade.
Three times Nvidia's drag came from Goldman Sachs
Share price, rather than company size, determines a constituent's influence on the price-weighted Dow. At about $870 per share, Goldman Sachs (GS) represents a tenth of the index. Its roughly 6% decline contributes around a fifth of the points lost. By contrast, Nvidia (NVDA), priced at about $180, has a 2% weighting; its 9% fall contributes about 6% of the decline. Despite falling more than the bank, the $4 trillion company exerted only about a third of its downward pull on the Dow.
The next-largest drag is Caterpillar (CAT), the constituent with the most direct exposure to the expansion now called into question by the election. In third-quarter results released on October 29, its power generation sales increased 30% to $3.42 billion, largely from turbines and large engines for data centres. Apple, Amazon, Alphabet, Microsoft and Nvidia, five of the biggest US technology companies, are all Dow members. Yet their combined contribution to the fall is less than a fifth. Banks, industrials, healthcare and the remaining constituents account for the other four fifths.
Banks face an additional concern: Senator Elizabeth Warren is expected to take over the Senate Banking Committee in January. She has already called on regulators to withdraw three bank capital proposals. JPMorgan (JPM) has fallen about 4%. Together, it and Goldman carry about 14% of the price-weighted Dow, compared with about 2% of the S&P 500. The committee's stance on bank capital therefore has a much greater impact on the Dow than on the broader index.
March 25 bill marked the push for a construction halt
On March 25, Senator Bernie Sanders and Representative Alexandria Ocasio-Cortez introduced the AI Data Center Moratorium Act. The bill would suspend new construction until Congress enacts artificial intelligence (AI) regulation. Following the results, Sanders renewed that demand on Wednesday. By then, lawmakers across at least 11 states had put forward their own proposals for pauses.
Voters supported restrictions in nearly all of the more than 40 local data-centre measures on Tuesday's ballots. In Texas and Ohio, both centres of the construction boom, Democrats secured the Senate seat and the governor's office after campaigns that featured data centres as an issue. A major share of planned capacity in Texas, Georgia and Ohio may encounter regulatory obstacles, Fitch said. UBS estimates that construction suspensions could jeopardise about 30% of capacity scheduled for 2028. During the session, Alphabet (GOOGL) unveiled a $17 billion data centre in Wyoming. Its shares nevertheless fell alongside the rest of the market.
65K payrolls forecast meets a December move already priced in
Markets paid no attention to Thursday's positive economic releases. For the week to October 31, initial jobless claims declined to 189K, versus a forecast of 196K, equalling the lowest figure since 1969. Productivity in the third quarter rose 3.6%, exceeding expectations of 2.5%. Unit labour costs dropped 0.7%, their first decline since the second quarter of 2025. Even so, the 10-year Treasury yield moved lower to about 4.85%.
Inflation pressures are spreading through the economy and the labour market could strengthen, according to Cleveland Fed President Beth Hammack. Richmond Fed President Tom Barkin identified inflation as the Fed's biggest risk, adding that AI expansion has increased demand. He also noted that data centres employ too few workers to create natural constituencies in their host communities. On October 28, the Fed left rates at 3.75%-4.00%. Ahead of the session, futures put the probability of an increase at the December 9 meeting at close to 80%.
Friday's October payrolls release is scheduled for 13:30 GMT. The forecast is 65K, following 29K in September, with unemployment expected to remain at 4.2% and average hourly earnings at 0.3% MoM. A reading close to expectations would keep the December increase in play, layering higher borrowing costs onto Thursday's concerns about slower construction. A weaker result would reduce the likelihood of an increase but substitute fears of a slowing economy, offering a different reason to sell the same index. This is the first of two payrolls reports available to the Fed before December 9. Futures have already priced the meeting before either report is released.
200-day average moves within reach
Resistance: Near 52,150, the 50-day Exponential Moving Average (EMA) is the initial hurdle. Wednesday delivered the first close above it since October 29, but that break held for only one session. Further resistance lies at the late-October high near 52,900, followed by Thursday's pre-open peak just below 53,800. That was where the rally following the results ran out of momentum.
Support: The first reference is Thursday's low just below 51,500, the weakest level since October 14. Next comes the October 14 low near 51,400. Beneath it, early-October lows around 51,000 form the foundation of the advance that began on October 1.
Bias: Maintain a short bias while closes remain capped by the 50-day EMA near 52,150. Target the early-October lows near 51,000 first, then the 200-day EMA near 50,800. The index has not traded at the latter since April 7. Near 57, the daily Stochastic Relative Strength Index (Stoch RSI) has moved halfway down from its late-October peak and continues to decline. A daily close above 52,150 would end the short position and leave Thursday as a one-day move, just as Wednesday was.
5-minute chart: Dow Jones Industrial Average
Dow Jones: frequently asked questions
Comprising the 30 most actively traded US stocks, the Dow Jones Industrial Average ranks among the world's oldest stock market indices. Share prices determine its weightings, rather than market capitalisation. To calculate it, the constituent share prices are added together and divided by a factor, currently 0.152. Its founder, Charles Dow, also established the Wall Street Journal. More recently, critics have argued that tracking only 30 conglomerates leaves it insufficiently representative, particularly compared with broader benchmarks such as the S&P 500.
The main influence on the Dow Jones Industrial Average (DJIA) is the combined performance of its constituents, as shown in their quarterly earnings reports. Other drivers include US and global macroeconomic releases, which shape investor sentiment. Interest rates set by the Federal Reserve (Fed) also matter: they determine the cost of borrowing, on which many corporations depend heavily. Inflation can consequently be a significant influence, alongside other indicators that inform Fed decisions.
Developed by Charles Dow, Dow Theory seeks to identify the stock market's primary trend. It compares the direction of the Dow Jones Industrial Average (DJIA) with that of the Dow Jones Transportation Average (DJTA), following a trend only when both move the same way. Trading volume provides confirmation, while analysis of peaks and troughs is another element of the method. The theory defines three phases: accumulation, as smart money begins buying or selling; public participation, as the broader public enters; and distribution, as smart money withdraws.
Investors can gain exposure to the DJIA through several instruments. ETFs offer a way to trade the index as one security without purchasing shares in each of its 30 constituents; the SPDR Dow Jones Industrial Average ETF (DIA) is a prominent example. Futures contracts allow traders to speculate on the DJIA's future value. Options give holders the right, without any obligation, to buy or sell the index at a specified price in the future. Mutual funds provide another route, allowing investors to purchase a share of a diversified portfolio of DJIA stocks and thereby obtain exposure to the overall index.
POPULAR ARTICLES
1BoJ minutes lift Yen as Ueda and US NFP take focus on Friday2Below 0.5600 again: Kiwi heads into New Zealand’s Saturday vote3One-Month High Reversal: Euro Under Pressure Ahead of Friday's US NFP4Pound surrenders BoE rate-hike gains ahead of Friday's US payrolls5Banxico's surprise rate cut sends Mexican Peso sliding as easing bets grow67% ETH decline: Ethereum price forecast as AI sell-off pressures crypto7Data-centre backlash wipes out Dow Jones Industrial Average’s midterm rally8Chinese Yuan: Gains Capped by PBoC Resistance – Societe Generale9$4,100 surpassed: Gold climbs as NASDAQ 100 plunges and December hike bets recede


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved