

Trading
Explora una amplia gama de mercados con precios competitivos, liquidez profunda y herramientas de trading avanzadas.
Más información 
Plataforma
Opera sin interrupciones con la potente plataforma de TMGM, diseñada para ofrecer velocidad, precisión y una experiencia de trading superior.
Más información Plataforma de trading
Herramientas de trading
Academia
Aprende los fundamentos del trading con recursos ideales para principiantes, incluidas guías, seminarios web y análisis del mercado.
Más información Academia TMGM
Noticias y análisis
Obtén actualizaciones del mercado en tiempo real y análisis de expertos para adelantarte a las oportunidades de trading
Más información Noticias y análisis
Acerca de
Descubre qué distingue a TMGM: nuestra presencia global, solidez regulatoria y compromiso con la innovación en el trading.
Más información Por qué elegir TMGM
Why is the US Dollar rising despite October Fed hike odds fading?
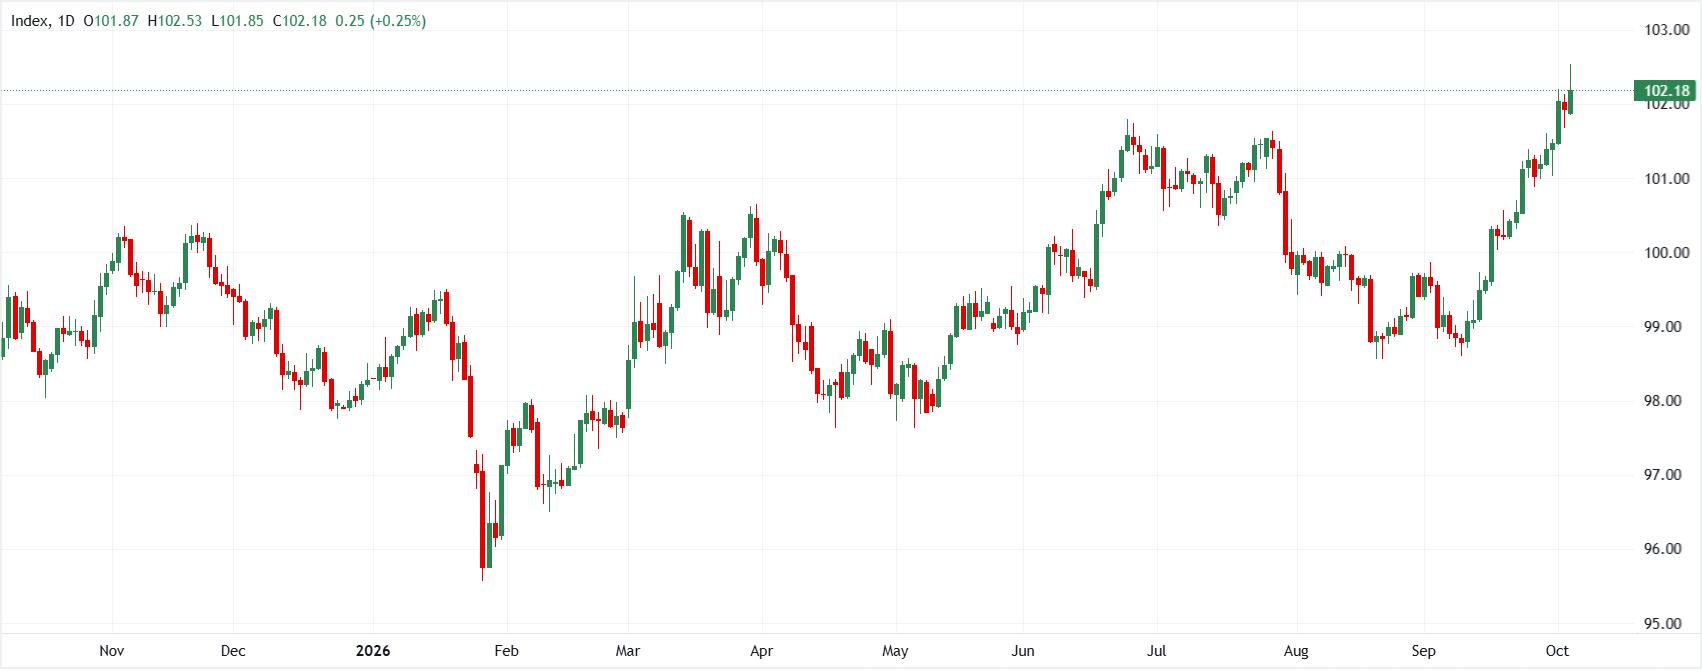
The US Dollar Index (DXY) is testing fresh yearly highs near the 102.50 zone, powered by independent Euro (EUR) weakness and relative resilience in the Federal Reserve's (Fed) rate path. However, as expectations for an October rate hike diminish following softer inflation and payrolls data, the fundamental drivers behind the Greenback’s momentum are coming under closer examination. While elevated US Treasury yields continue to lend broad support, market strategists are increasingly divided over whether rising term premia and upcoming US midterm election risks will stall the US Dollar's advance or if overseas monetary policy easing will keep the Greenback on a bullish trajectory.
Fading Fed hike expectations and fiscal yield drivers challenge USD momentum
Philip Wee at DBS Group Research cautions that the US Dollar's recent rally is running out of monetary policy impetus as senior Fed officials push back against a rate hike at the October 28 FOMC meeting. With softer PCE inflation and payrolls data altering rate expectations, attention is shifting to the composition of rising long-term US Treasury yields. Wee stresses that yields elevated by fiscal deficits, debt issuance, and term premia offer far less structural support to the Greenback than central bank tightening, while upcoming US midterm elections pose additional risks to the broader macro outlook.
"Higher yields driven by Fed tightening can support the USD. Higher term premia driven by concerns over debt supply, fiscal sustainability, and Treasury-market credibility need not. The November 3 US midterm elections add another constraint... If Republicans lose control of the House, markets could also reassess the US exceptionalism narrative that supported the USD..."
Euro weakness and resilient Fed outlook keep DXY upside target at 102.85
Taking a pro-US Dollar view, Chris Turner at ING emphasizes that the Greenback continues to gain ground against major peers, primarily fueled by heavy selling in the Euro. Despite soft September US labor data, markets remain comfortable with an October hold followed by a December Fed rate hike. With the European Central Bank’s (ECB) rate path subject to sharper dovish repricing compared to the Fed's, relative yield differentials and upcoming ISM services and FOMC minutes should continue to support DXY toward 102.85.
"DXY dollar index is pushing smartly to new highs of the year. It is being propelled by the sell-off in the euro, which represents 58% of the DXY basket. 102.85 would seem to be the next upside target here... Core support for the dollar should continue to come from the fact that expectations for the monetary policy tightening cycle remain far more resilient for the Fed than for overseas central banks – especially the ECB."
Key Takeaway
The US Dollar's move to fresh yearly highs near 102.50 demonstrates how central bank divergence and overseas weakness — particularly in the Eurozone — can sustain Greenback momentum even as the Fed pauses its tightening cycle. While DBS Group Research warns that elevated term premia and November midterm political headwinds could undermine the "US exceptionalism" trade, ING projects that smaller rate cut adjustments for the Fed relative to aggressive dovish repricing at the ECB will keep the US Dollar well-supported through year-end.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
Artículos destacados
1Australian Dollar: Downside limited against US Dollar – UOB2British Pound recovers some losses against US Dollar, ISM Services PMI eyed3Euro: Pressured yet systemic risk contained – DBS4Silver Price Forecast: XAG/USD jumps to near $61.80 as hawkish Fed bets recede5USD/CHF Price Forecast: Holds below 0.8320 as the Swissie withstands bonds selloff6Gold struggles as dovish Fed repricing meets stronger US Dollar, elevated yields7Why is the US Dollar rising despite October Fed hike odds fading?8Crypto Today: Bitcoin rally slows while Ethereum and XRP extend recovery amid slowing ETF inflows9AI Tokens Price Prediction: Capital rotation fuels FET, VIRTUAL, and NEAR rallies
COTIZACIONES EN VIVO


¡Comience ahora!
Regístrese y acceda a los mercados globales en menos de 3 minutos

Conéctese con nosotros









Contactos
Teléfono: +61 2 8036 8388
Fax: +61 2 8036 8388
Correo electrónico: support@tmgm.com
Web: https://www.tmgm.com



La información proporcionada en este sitio web es únicamente de carácter general y no constituye asesoramiento financiero personal. Antes de actuar sobre cualquier información de este sitio web, debe considerar la idoneidad de la información en relación con sus objetivos, situación financiera y necesidades. Invertir en CFD y contratos de margen de FX conlleva riesgos significativos y no es adecuado para todos los inversores. Puede perder más que su depósito inicial. Usted no posee ni tiene ningún interés en el activo subyacente. Le recomendamos que busque asesoramiento independiente y se asegure de comprender plenamente los riesgos involucrados antes de operar. Es importante que lea y considere el documento de divulgación antes de adquirir cualquier producto listado en el sitio web. La información y los anuncios ofrecidos en este sitio web no están destinados al uso por parte de ninguna persona en ningún país o jurisdicción donde dicho uso sea contrario a las leyes y regulaciones locales. Los productos y servicios ofrecidos en este sitio web no están destinados a residentes de Estados Unidos, Malasia y Tailandia.
TMGM está autorizado y regulado en varias jurisdicciones.
Trademax Australia Limited, que opera como TMGM, está regulada por la Comisión Australiana de Valores e Inversiones (ASIC), AFSL n.º 436416, y está ubicada en Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Correo electrónico: support@tmgm.com.au
Trademax Global Limited, que opera como TMGM, está autorizada y regulada por la Comisión de Servicios Financieros de Vanuatu (VFSC), número de registro 40356, y está registrada en 1276, Kumul Highway, Port Vila, Vanuatu, República de Vanuatu.
Correo electrónico: support@tmgm.com
Trademax Global Markets (SE) Limited, que opera como TMGM, está autorizada y regulada por la Autoridad de Servicios Financieros (FSA) de Seychelles, con número de licencia SD224. La empresa está registrada en Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Correo electrónico: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, que opera como TMGM, está autorizada y regulada por la Comisión de Servicios Financieros de Mauricio (FSC) con licencia n.º GB22201012, y está registrada en 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauricio.
Correo electrónico: support@tmgm.com
Copyright © TMGM. Todos los derechos reservados