
News & AnalysisCareer

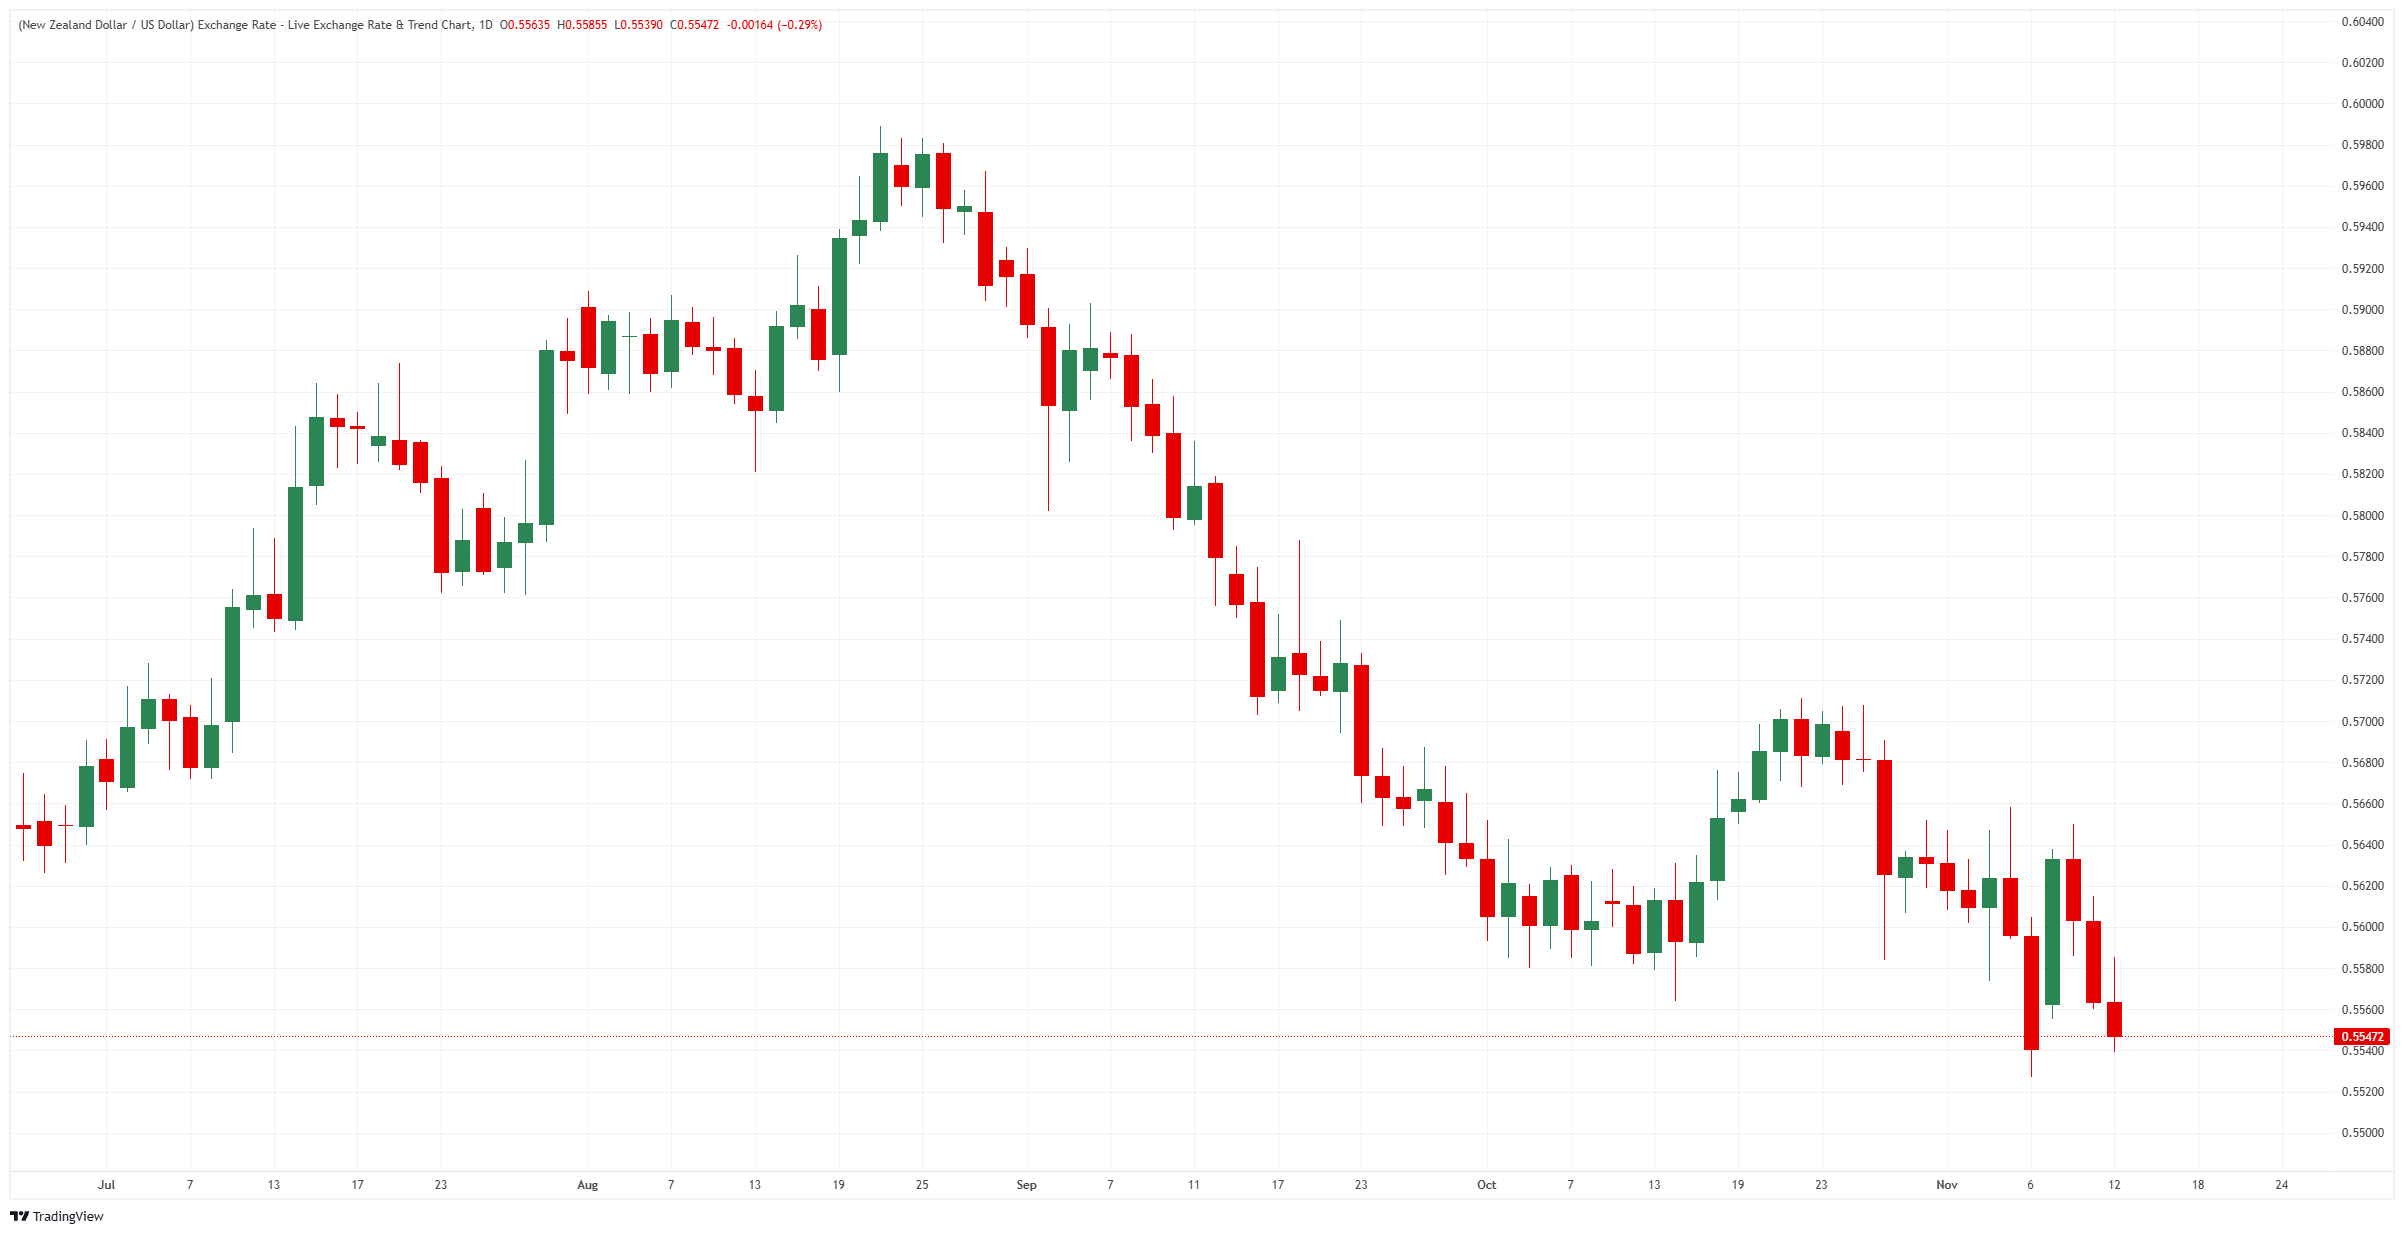
At around 0.5550, NZD/USD is trading just above Thursday’s low, having retreated for three consecutive sessions. The Kiwi’s post-election recovery on Monday lasted just one session, leaving the pair once again close to its weakest level in more than 18 months. It now sits below the starting point of Monday’s rebound and only a short distance above the 6 November low.
Further monetary tightening will be necessary, San Francisco Fed President Daly said on Thursday, although she gave no indication of its scale or timing. Futures markets fully price in a rate increase on 9 December. By contrast, the Reserve Bank of New Zealand (RBNZ) left its Official Cash Rate (OCR) unchanged at 2.75% on 28 October. With US rates at 3.75%-4.00%, a Fed increase would extend an interest-rate differential already measuring at least a full percentage point.
With nearly 400K votes still to be counted by 27 November, preliminary results from New Zealand’s 7 November election allocate 67 of 131 seats to National, ACT and New Zealand First, one more than required for a majority. Labour would restore employment to the RBNZ’s mandate. Against unemployment of 5.7%, that points towards lower interest rates for the Kiwi. Meanwhile, the Business NZ manufacturing index slipped from 56.5 to 54.9 in October, easing pressure on the RBNZ to follow the Fed’s lead.
Following September’s reading of 50.9, Business NZ’s services index is scheduled for 21:30 GMT on Sunday. Next comes the RBNZ’s Financial Stability Report at 20:00 GMT on Monday. Its quarterly inflation expectations survey, which informs the bank’s next rate decision, follows at 02:00 GMT on Tuesday, 17 November; the previous reading was 2.34%.
Before those releases, US producer price figures arrive at 13:30 GMT on Friday, followed by another speech from San Francisco Fed President Daly at 17:00 GMT. October retail sales are scheduled for 13:30 GMT on Tuesday, 17 November, with no change forecast after a 0.8% increase. Both data releases will feed into the Fed’s 9 December decision.
Rebounds have formed progressively lower peaks since August, reaching just below 0.6000 on 21 August, around 0.5700 in late October and 0.5650 on 10 November. On the daily chart, which begins in late June, the lowest level is the 6 November trough between 0.5500 and 0.5550. Four of the past five sessions have ended in declines for the pair.
The health of New Zealand’s economy and its central bank’s policy broadly determine the value of the New Zealand Dollar (NZD), a widely traded currency also known to investors as the Kiwi. Several more specific influences can also affect its performance. As China is New Zealand’s largest trading partner, developments in the Chinese economy tend to move the Kiwi. Weak Chinese economic news is likely to mean fewer New Zealand exports to that market, weighing on the domestic economy and, in turn, the currency. Dairy prices are another important influence, given that dairy is New Zealand’s main export. Higher prices lift export earnings, supporting both the economy and NZD.
Keeping inflation within a 1% to 3% range over the medium term, and close to the 2% midpoint, is the Reserve Bank of New Zealand’s (RBNZ) objective. The bank sets interest rates at a level intended to achieve that aim. If inflation is too high, the RBNZ raises rates to slow the economy. Higher rates also lift bond yields, making investment in New Zealand more attractive and thereby supporting NZD. Rate reductions, by contrast, generally weaken the currency. NZD/USD can also be strongly influenced by the interest-rate differential: the gap between current or expected New Zealand rates and those set by the US Federal Reserve.
By helping investors assess the economy’s condition, New Zealand’s macroeconomic releases can affect the valuation of the New Zealand Dollar (NZD). Robust growth, low unemployment and strong confidence underpin a healthy economy and support the currency. Strong economic growth draws foreign investment and, when accompanied by elevated inflation, may prompt the Reserve Bank of New Zealand to raise interest rates. Weak economic figures, on the other hand, are likely to lead to NZD depreciation.
When investors are optimistic about growth and judge wider market risks to be low, the New Zealand Dollar (NZD) generally gains strength. These risk-on conditions tend to improve the outlook for commodities and so-called ‘commodity currencies’ such as the Kiwi. Market turbulence or economic uncertainty usually has the opposite effect: investors sell higher-risk assets in favour of more stable safe havens, and NZD tends to weaken.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


