
News & AnalysisCareer

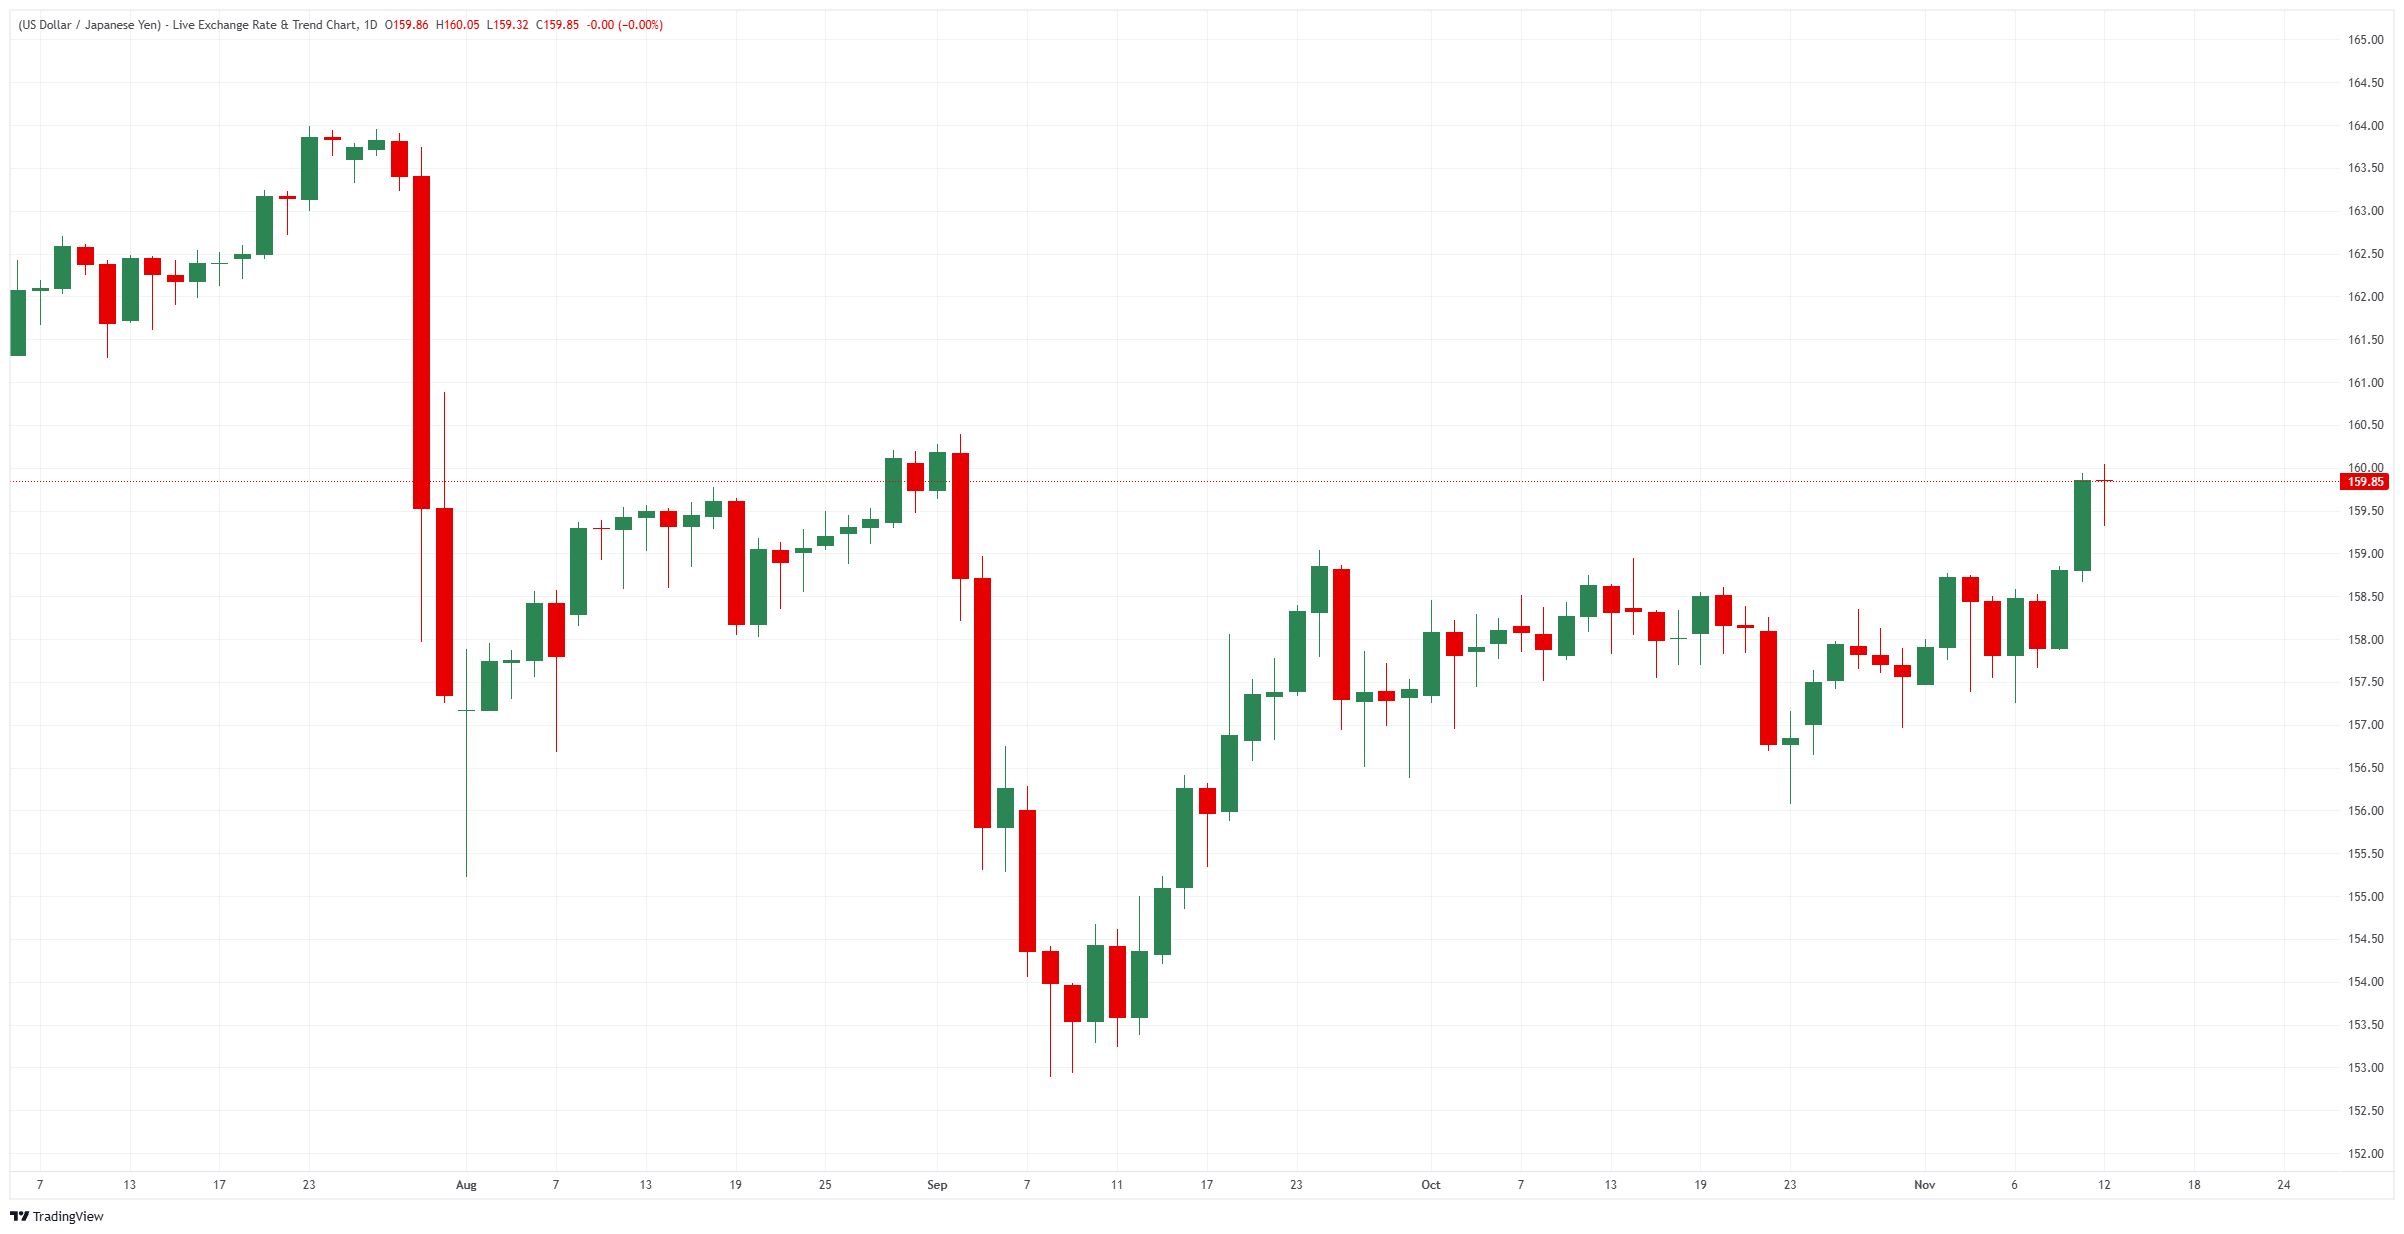
At 160.00, the level at which Japan has bought yen twice this year, USD/JPY met resistance on Thursday after reaching it for the first time since early September. Having peaked marginally above that threshold, the pair is now trading just below it, virtually unchanged from its opening level. The last sizeable move came on Wednesday, when it broke out of its trading range.
Recent currency moves have been too rapid, Japan's Vice Finance Minister for International Affairs Mimura said on Thursday, warning that the summer's intervention should not be forgotten. Between 30 July and 3 August, Japan spent a record JPY 15.4 trillion. On Thursday, the New York Fed confirmed that the US Treasury had purchased yen during the third quarter. Although that operation pushed the pair down from around 164.00 to roughly 155.00, it has since returned to within about four yen of its starting point.
Following weak demand at a 30-year auction, the 10-year Treasury yield climbed to around 5.12% on Thursday, with a Fed rate increase on 9 December fully priced in. The dollar strengthened against the euro, the pound and the Kiwi, yet USD/JPY remained unchanged. The Bank of Japan (BoJ) rate stands at 1.25%, compared with the Fed's 3.75%-4.00%.
A speech by New York Fed President Williams is scheduled for 23:30 GMT on Thursday. Attention then turns to Friday's US producer price figures at 13:30 GMT: a monthly increase of 0.4% is forecast, following 1.3%. The release has implications for the size of the Fed's December rate rise.
Growth of 0.1% quarter on quarter, following 0.4%, is forecast for Japan's preliminary third-quarter Gross Domestic Product (GDP), due at 23:50 GMT on Sunday. At 04:00 GMT on Monday, BoJ board member Takata will speak, having voted for a rate rise on 30 October. October's national inflation figures are then due at 23:30 GMT on Thursday, 19 November. These three events all precede the BoJ's 18 December decision, at which a rate increase is widely anticipated.
The 157.00-159.00 range had contained USD/JPY since late September until Wednesday's advance carried it higher. Around three-fifths of the decline from the late-July peak to September's low near 153.00 has now been retraced. By contrast, Thursday's trading bar is narrow: the low is a little below 159.50, while the opening and latest prices are virtually the same.
Among the world's most actively traded currencies, the Japanese yen (JPY) broadly reflects the performance of Japan's economy. More specific influences include Bank of Japan policy, the gap between Japanese and US bond yields, and traders' appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan's mandate, making its actions an important influence on the yen. Direct intervention in currency markets has occurred on occasion, usually with the aim of weakening the currency. However, political concerns among Japan's main trading partners discourage frequent intervention. Between 2013 and 2024, the BoJ's ultra-loose monetary policy weakened the yen against its major peers as the policy gap between Japan's central bank and other leading central banks grew. More recently, a gradual withdrawal of that ultra-loose stance has provided the yen with some support.
By maintaining ultra-loose monetary policy over the past decade, the BoJ increasingly diverged from other central banks, notably the US Federal Reserve. That divergence helped widen the gap between 10-year US and Japanese bond yields, benefiting the US dollar relative to the Japanese yen. The differential is now narrowing as a result of the BoJ's 2024 decision to move gradually away from ultra-loose policy, together with interest-rate reductions by other major central banks.
Investors often regard the Japanese yen as a safe-haven asset, attracted by its perceived reliability and stability when markets come under strain. During such periods, they are more likely to allocate money to the Japanese currency. Market turbulence is therefore likely to lift the yen against currencies considered riskier investments.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


