
News & AnalysisCareer

Growth of 0.7% in the three months to September is the market forecast for the United Kingdom’s (UK) preliminary third-quarter Gross Domestic Product (GDP) estimate, up from 0.5% in the second quarter of 2026. Due from the Office for National Statistics on Thursday, the release is the main event on this week’s UK economic calendar. The annual growth rate is expected to rise to 1.9%, compared with 1.4% in the previous month.
Industrial Production is forecast to have increased by 3% in the 12 months to September, up from 1.6% in August, making it one of the expected principal contributors to UK economic growth. Confirmation of that strength would create a favourable backdrop for the Bank of England (BoE) to continue the monetary tightening cycle it began last week.
Expectations for third-quarter economic growth have improved as recent UK macroeconomic releases have proved surprisingly resilient to the uncertainty surrounding the war in the Middle East and higher oil prices.
Manufacturing strength helped August’s monthly GDP figures exceed forecasts when released last month, with output expanding by 0.1% rather than contracting by the 0.1% markets had anticipated. A 0.8% increase in factory output during August largely offset stagnation in services and a 0.2% fall in construction output.
Further evidence of resilience came from the UK Manufacturing and Services Purchasing Managers’ Index (PMI) readings, which showed business activity still expanding in October. Unemployment, meanwhile, fell to its lowest rate since July last year. This broadly healthy macroeconomic backdrop has led the International Monetary Fund to lift its UK growth projection for 2026 from 1% to 1.3%.
A neutral UK budget has also helped sustain the favourable economic backdrop, easing concerns over the sizeable public debt, at least for the time being, and supporting the British Pound. Higher taxes on banks and gambling companies are expected to fund lower charges on food and energy bills. Despite concerns about their response, bond markets have registered no significant objection to the plans.
Against this backdrop, last week’s Bank of England rate rise means the third-quarter GDP report will face close scrutiny. Although economic growth is not a specific target within the BoE’s mandate, a healthy GDP reading would undoubtedly ease its rate-setting task while consumer inflation remains stubbornly high.
For the first time in three years, the BoE tightened monetary policy last week. Governor Bailey was among the policymakers who indicated that further rate increases might be necessary to return inflation to target. On Tuesday, Deputy Governor Clare Lombardelli took a stronger position, stating that she “would not rule out rate hike possibility in December”. A robust GDP figure on Thursday would lend support to those views and could encourage speculative buying of the Pound.
Thursday at 07:00 GMT is the scheduled release time for the UK’s preliminary Q2 GDP estimate. Moderate growth is anticipated for the three months to June. Risks for GBP/USD are tilted towards gains: a reading above expectations would increase the likelihood of another BoE rate rise, most likely in February.
Strong US inflation figures and hawkish remarks from Fed speakers drove broad US Dollar gains on Tuesday, triggering a sharp reversal in GBP/USD. At the time of writing, the pair is trading around 1.3320. Sellers have forced it beneath the lower boundary of the ascending channel in place since October. Momentum signals on the 4-hour chart have also shifted into bearish territory: the Relative Strength Index (14) is nearing oversold levels, while red bars on the Moving Average Convergence Divergence (MACD) histogram are widening.
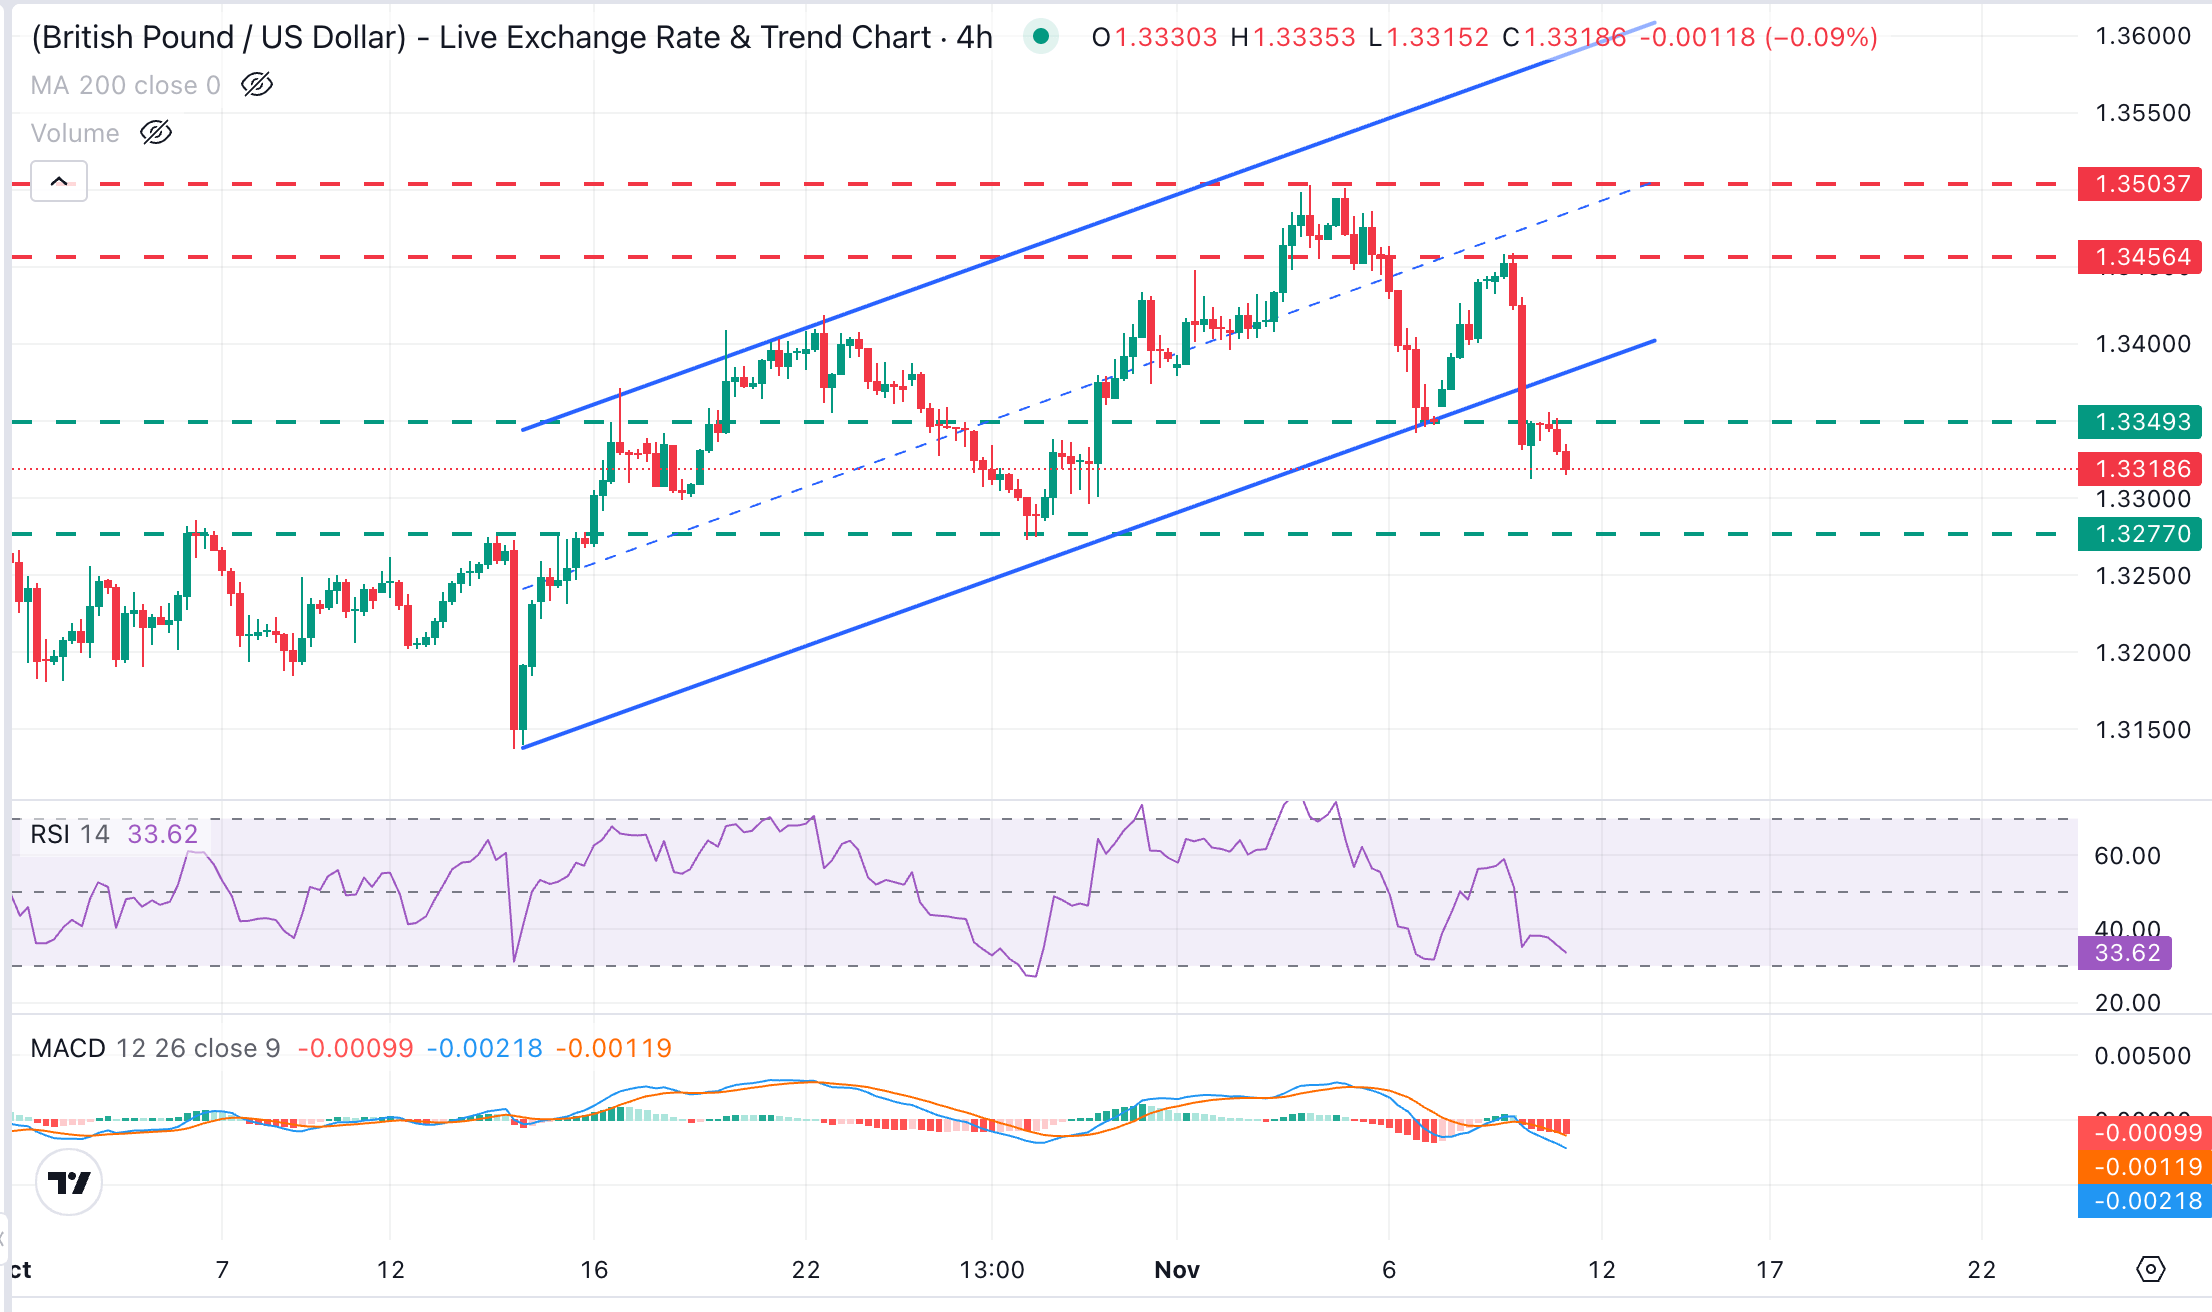
FXStreet FX Analyst Guillermo Alcalá offers this assessment: “Recent GBP/USD price action suggests that the corrective recovery from mid-October lows might have come to an end, and that the pair is ready to resume the broader bearish trend.”
Alcalá outlines the downside scenario as follows: “While below the channel bottom and the November 6 low, near 1.3340, bears are likely to be tempted to revisit the late October lows near 1.3270, with their gaze on the key resistance area near 1.3130,”
For an upward move, the requirement is clear in Alcalá’s view: “The pair would need to return above the broken trendline support, now around 1.3380, to ease bearish pressure, and shift the focus back towards the November 10 high near 1.3460 and the November peak, in the 1.3500 area.”
Published monthly and quarterly by the Office for National Statistics, Gross Domestic Product (GDP) captures the total value of goods and services produced in the UK over a specified period. It is regarded as the principal gauge of UK economic activity. The quarter-on-quarter (QoQ) figure measures activity in the reference quarter against the preceding quarter. An increase in the indicator is generally viewed as supportive of the Pound Sterling (GBP), whereas a low reading is considered negative for the currency.
Find out more.Upcoming release: Thu 12 Nov 2026 07:00 (Prel)
Release frequency: Every quarter
Market consensus: 0.7%
Prior reading: 0.5%
Data source: Office for National Statistics
A steady inflation rate of 2%, or ‘price stability’, is the primary objective of the Bank of England (BoE), which determines the United Kingdom’s monetary policy. To pursue this goal, it adjusts base lending rates. By setting the rate at which it lends to commercial banks and at which banks lend to one another, the BoE determines interest rates across the wider economy. These decisions also affect the value of the Pound Sterling (GBP).
Inflation above the Bank of England’s target prompts it to raise interest rates, increasing borrowing costs for households and businesses. Sterling benefits because higher rates make the UK a more appealing destination for global investors’ funds. By contrast, below-target inflation signals slowing economic growth. In those circumstances, the BoE will consider cutting rates to make borrowing cheaper, hoping businesses will use credit to invest in projects that generate growth. This is negative for the Pound Sterling.
When interest rate cuts cannot deliver the required result, the Bank of England can turn to Quantitative Easing (QE) as a last resort in extreme circumstances. The policy substantially expands the flow of credit through a stalled financial system. To carry out QE, the BoE prints money and uses it to purchase assets from banks and other financial institutions – typically government bonds or AAA-rated corporate bonds. The Pound Sterling usually weakens as a result.
As the economy strengthens and inflation begins to rise, Quantitative Tightening (QT) reverses the process of QE. Under QE, the Bank of England (BoE) buys government and corporate bonds from financial institutions to encourage lending. Under QT, however, it ceases further bond purchases and no longer reinvests the principal repaid when bonds in its existing holdings mature. The policy is generally supportive of the Pound Sterling.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved


