

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Rising US rate bets see euro edge towards the lower end of its range
- A dip below 1.1150 leaves EUR/USD with little of Monday's advance intact.
- A gap of up to two percentage points could open between Fed rates and the ECB's 2.50% deposit rate.
- Ahead of Friday's Eurozone GDP release, ECB President Lagarde is scheduled to speak twice.
The Euro has surrendered nearly all of Monday's advance, slipping just below 1.1150 before edging back above that mark. Stronger-than-forecast US consumer prices have pushed it into the lower half of the 1.1100-1.1300 range, where it has now traded for five weeks.
Traders assign roughly a 74% probability to a second quarter-point Fed hike by January, after Dallas Fed President Logan called for two more such increases before a pause. The backdrop was an October rise of 0.3% in core US consumer prices, exceeding the 0.2% forecast. Unless the European Central Bank (ECB) also raises rates, two US hikes would leave them 1.75-2.00 percentage points above its 2.50% deposit rate.
While two Fed officials quantified their rate expectations, ECB Chief Economist Lane said he would require a high bar to be met before signalling the ECB's next rate moves. With Eurozone inflation reaching a three-year high of 4% in October, money markets are pricing in two ECB hikes by mid-2027. Those increases would reduce the rate differential for the Euro.
Which events are next on the calendar?
Whether the ECB also raises rates in December will be informed by ECB President Lagarde's comments and Friday's updated third-quarter Eurozone Gross Domestic Product (GDP) reading. Lagarde is due to speak on Wednesday at 09:45 GMT and Thursday at 19:30 GMT, followed by ECB Executive Board member Schnabel on Friday at 07:10 GMT. The GDP release follows at 10:00 GMT on Friday, with growth forecast at 0.4%, unchanged from the initial estimate.
With the Fed's December 9 rate hike already priced in, the US calendar includes remarks from Cleveland Fed President Hammack, who has a vote this year, on Thursday at 14:00 GMT. Friday's core producer price release is due at 13:30 GMT; the forecast is for annual growth to remain at September's 5%.
What does the chart show?
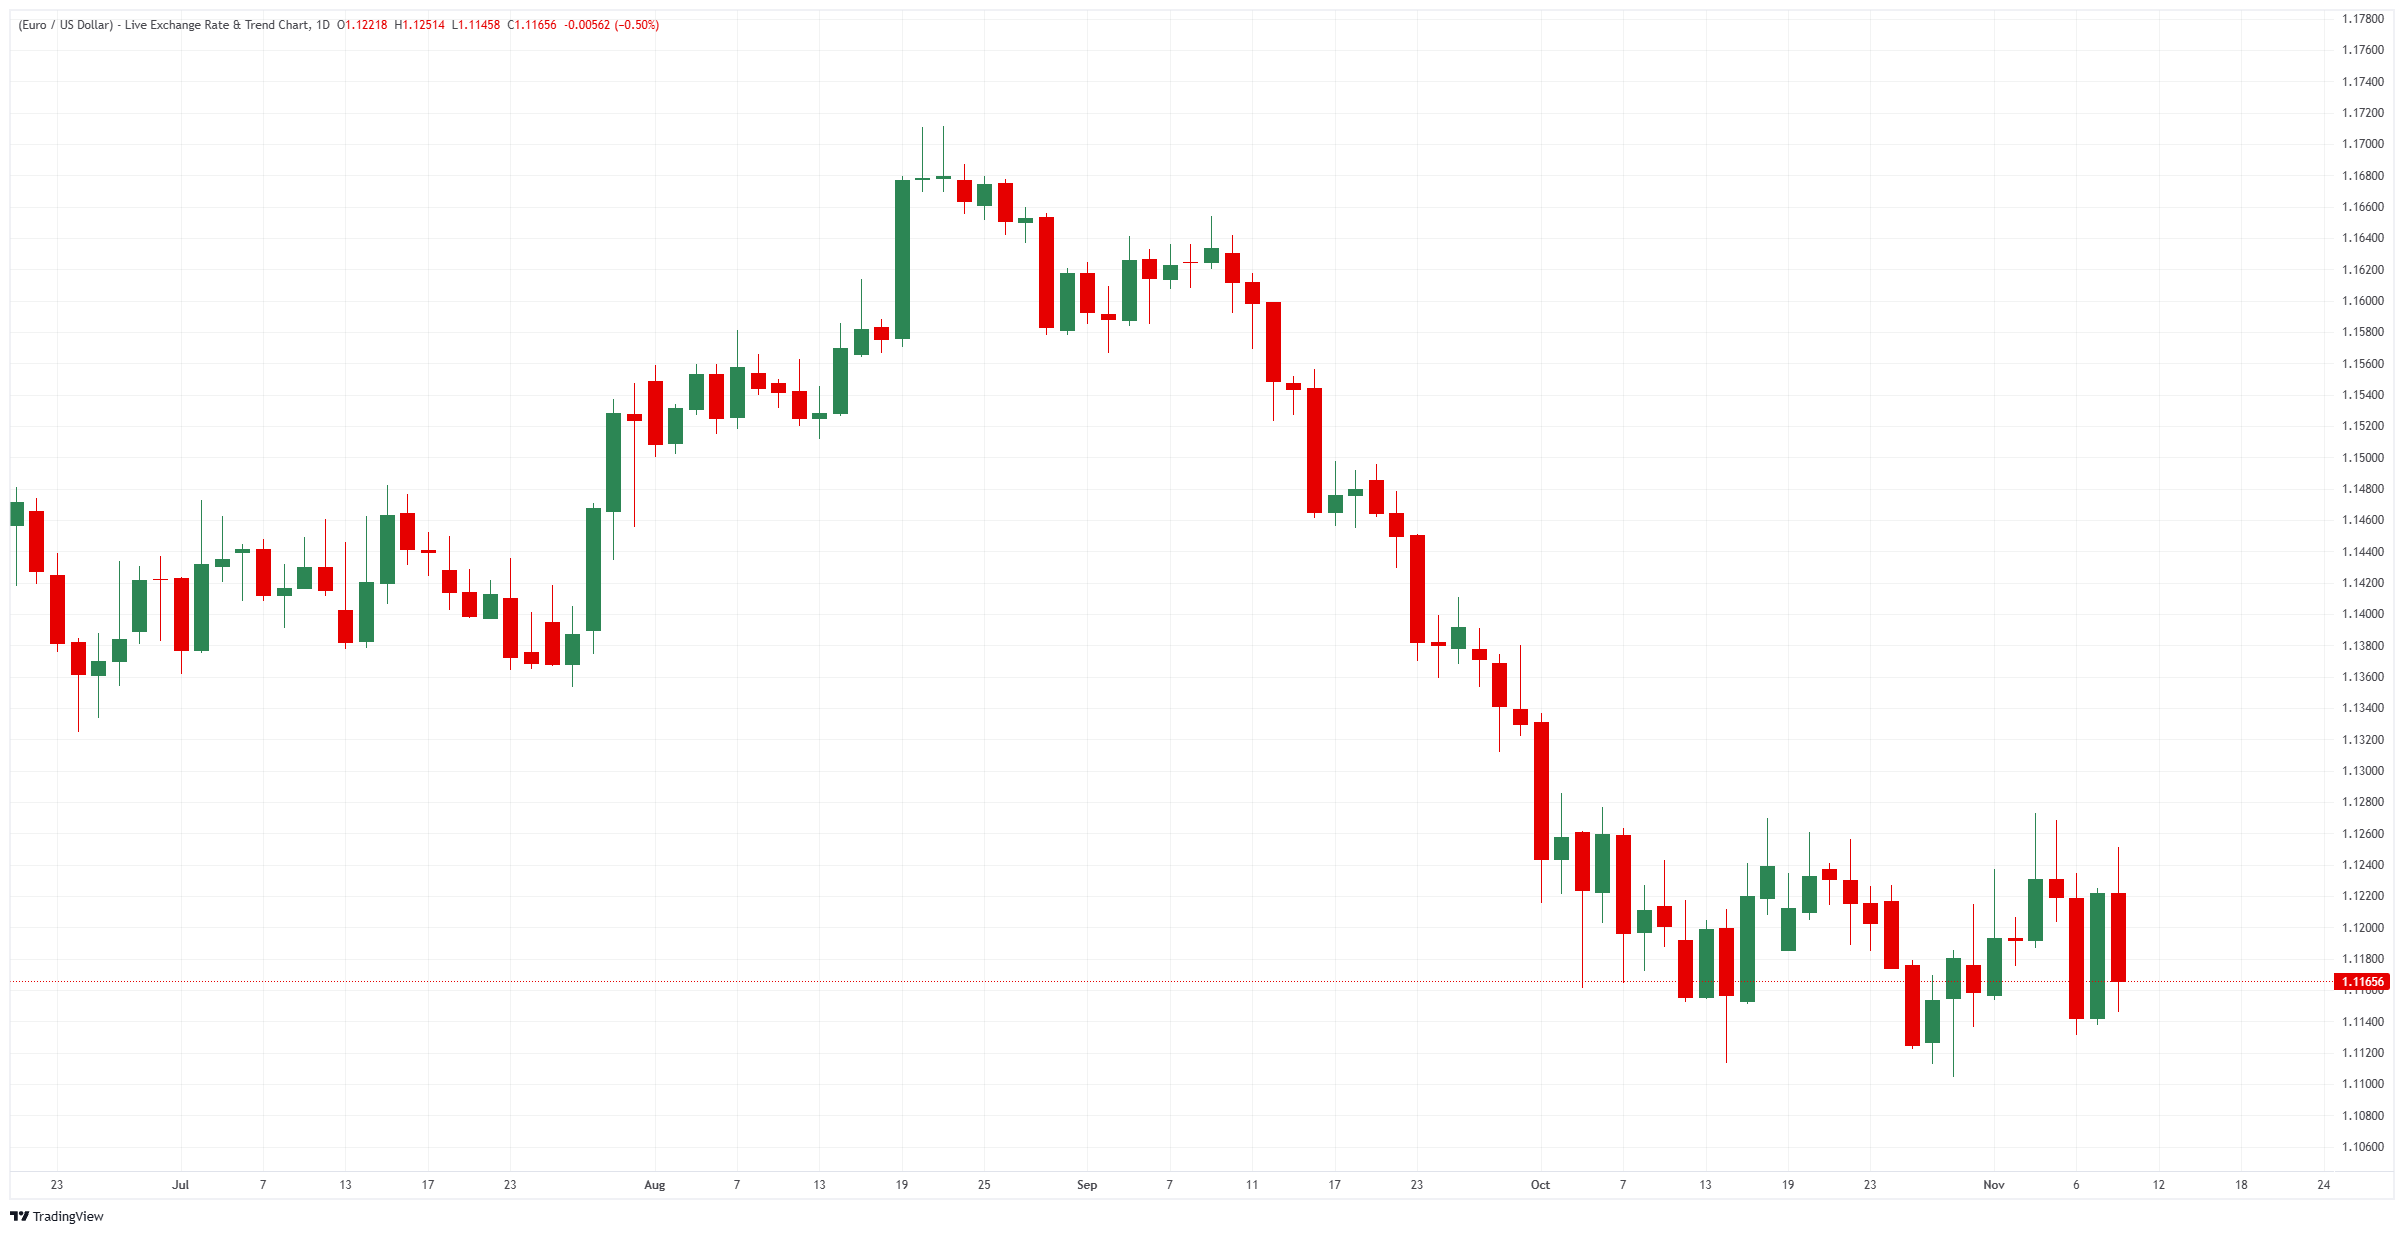
A decline of about 5% from the Euro's late-August peak near 1.1700 preceded its entry into the current range. Repeated attempts to reach the upper boundary have reversed just short of it, most recently on November 5. At the lower end, the lows recorded on October 14 and October 29 remained just above the range floor.
Daily price chart: EUR/USD
Common questions about the Euro
Used by the 20 European Union countries within the Eurozone, the Euro ranks behind only the US Dollar in global currency trading. Its share of all foreign exchange transactions stood at 31% in 2022, with average daily turnover exceeding $2.2 trillion. An estimated 30% of all transactions involve EUR/USD, making it the world's most traded currency pair. It is followed by EUR/JPY at 4%, EUR/GBP at 3% and EUR/AUD at 2%.
Based in Frankfurt, Germany, the European Central Bank (ECB) serves as the Eurozone's reserve bank, determining interest rates and overseeing monetary policy. Maintaining price stability is its central mandate, whether through curbing inflation or supporting growth. Adjustments to interest rates are its main policy instrument. The Euro generally benefits when rates are relatively high, or are expected to rise; the reverse also applies. Monetary policy is decided by the ECB Governing Council, which meets eight times a year. The decision-makers comprise the heads of the Eurozone's national banks and six permanent members, among them ECB President Christine Lagarde.
The Harmonized Index of Consumer Prices (HICP), which measures Eurozone inflation, is a key economic gauge for the Euro. An inflation reading above expectations, particularly one exceeding the ECB's 2% target, obliges the central bank to increase interest rates to regain control of price pressures. When rates are relatively high compared with those elsewhere, the Euro usually gains support, as global investors find the region a more attractive destination for their funds.
The Euro can respond to data releases that indicate the economy's health. GDP, Manufacturing and Services PMIs, employment figures and consumer sentiment surveys are among the indicators that can move the single currency. Economic strength supports the Euro by drawing in more foreign investment and potentially prompting the ECB to raise interest rates, which would directly strengthen the currency. Weak economic readings, by contrast, are likely to weigh on the Euro. Particular attention is paid to Germany, France, Italy and Spain, the euro area's four largest economies, as together they represent 75% of the Eurozone economy.
The Trade Balance is another key release for the Euro, showing the gap between a country's export earnings and its spending on imports over a specified period. Strong overseas demand for a country's exports creates additional demand for its currency as foreign buyers seek to purchase those goods, lifting the currency's value. A positive net Trade Balance therefore supports a currency, while a negative balance has the opposite effect.
POPULAR ARTICLES
1GBP/JPY Price Forecast: Are Bulls Stalling Near 213.00 as SMA Resistance Holds?2New Zealand Dollar’s election gain nearly halved after US CPI3Yen approaches 159.00 as Treasuries climb back above 5%4Rising US rate bets see euro edge towards the lower end of its range5Can the pound regain 1.34 after falling below it on hotter-than-expected US inflation?6Hot CPI and Nvidia weigh on US indices as Nasdaq 100 leads declines7CPI points to persistent US inflation pressures, Fed’s Bowman warns8Could underlying inflation rise as energy prices fall? ECB’s Lane flags the risk9Fed’s Schmid flags broader inflation pressures beyond energy as policy remains loose


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved