

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Can the US Dollar Index Extend Gains After Hitting a Fresh Year-to-Date High of 103.08 as Fed Rate Hike Bets Rise?
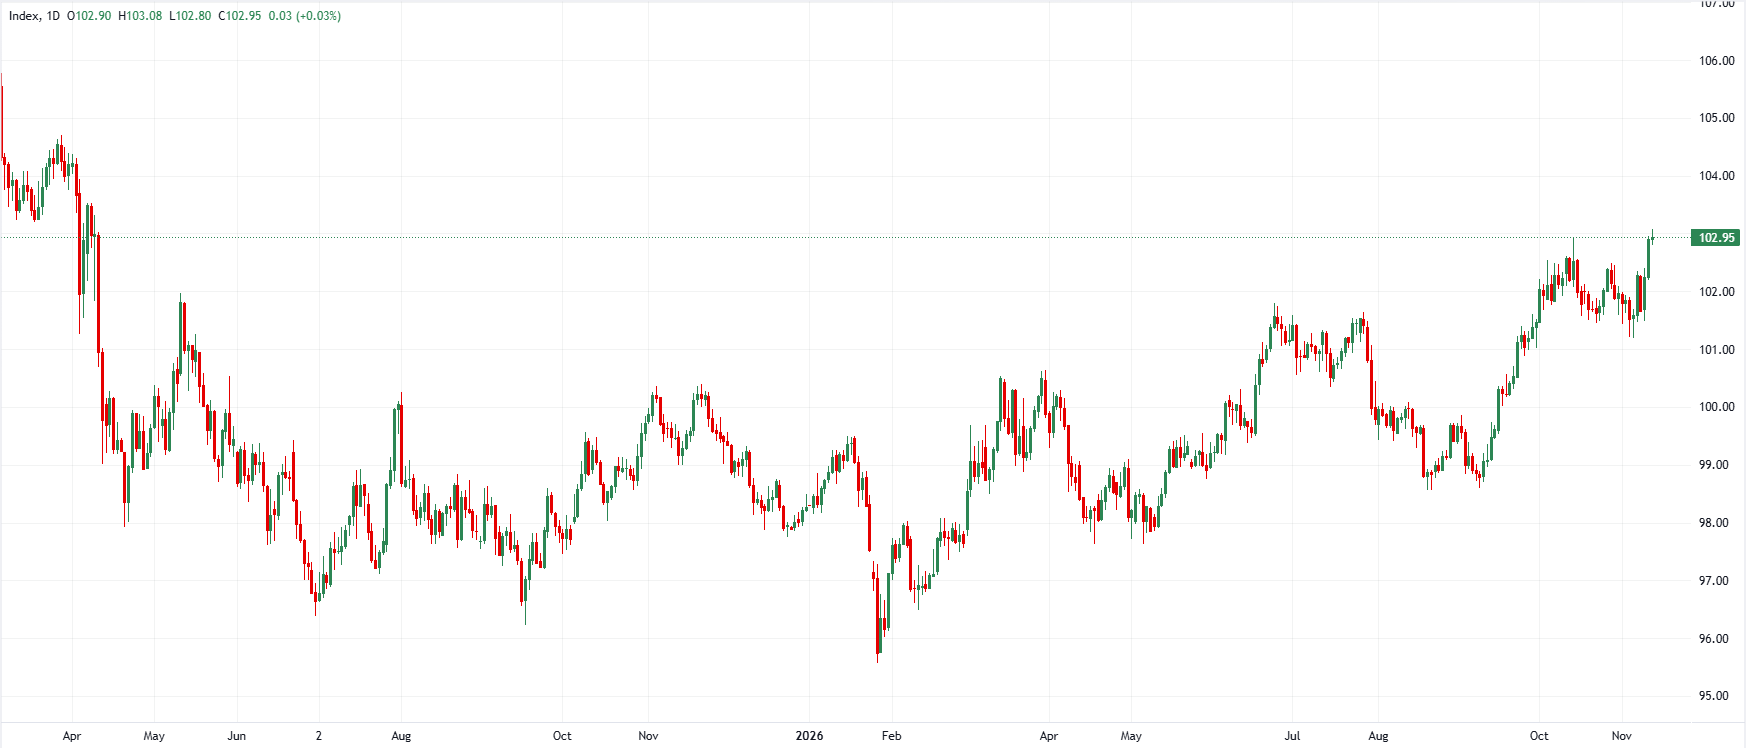
Broad-based gains in the US Dollar (USD) across global foreign exchange markets have pushed the US Dollar Index (DXY) to a new year-to-date peak of 103.08, taking the currency back to levels last seen in April 2025. Real front-end rate differentials underpin the latest advance: stronger-than-expected US inflation readings and hawkish commentary from the Federal Reserve (Fed) have led traders to price in a quicker pace of monetary tightening. The Greenback is also drawing support from easing worries about political interference at the Fed and sustained safe-haven inflows. Further near-term gains are indicated by inflation releases and Fed communication, according to institutional strategists at MUFG, ING, and Rabobank. However, they regard medium-term pressure from the US fiscal deficit as an important variable in the US Dollar's wider outlook.
Could consecutive December and January Fed hikes support the US Dollar? MUFG's assessment
A faster Federal Reserve tightening cycle is increasingly being priced in after the latest strong US inflation readings, according to Lee Hardman at MUFG. He attributes the US Dollar Index DXY's new year-to-date high of 103.08 to those expectations. Hardman does not expect a 50 bps increase in December, but futures markets signal consecutive 25 bps hikes in December and January. Forthcoming remarks from New York Fed President John Williams will therefore be crucial in confirming the rate trajectory.
"The US dollar has continued to strengthen overnight resulting in the dollar index hitting a fresh year-to-date high of 103.08. The US dollar’s renewed upward momentum has been encouraged by expectations that the Fed is likely to speed up the pace of rate hikes in response to the recent run of stronger US inflation data... There are currently around 28bps of hikes priced by December, and 43bps of hikes priced by the following meeting in January indicating that even if the Fed hikes by 25bps in December it is now expected to quickly follow up with another 25bps hike at the start of next year... While we don’t expect a larger 50bps hike to be delivered in December, it is more likely now that the Fed could hike rates back-to-back in December and January."
Can front-end rate differentials and PPI drive further US Dollar gains? ING's view
Real front-end yield differentials, rather than overstretched speculative positioning, explain the US Dollar's fundamentally supported, rates-led recovery to April 2025 levels, argue Francesco Pesole and the FX strategy team at ING. A 50 bps December hike has been raised as a possibility by Fed Governor Chris Waller, whereas markets are still pricing in 28 bps. That gap leaves clear room for a hawkish repricing, in ING's assessment, with the forthcoming Producer Price Index (PPI) release a possible catalyst for additional USD strength.
"The combination of hawkish Fedspeak and a US CPI beat earlier this week continues to pay dividends for the dollar. DXY is now back at Liberation Day (April 2025) levels, with real front-end rate differentials continuing to fuel strong dollar momentum. Importantly, this remains a rates-driven move, with contained excessive USD strength relative to short-term fair value currently built in... We continue to see upside risks for the dollar in the coming days. The Fed's Chris Waller has put a 50bp December move on the radar, and that should keep markets biased towards hawkish interpretations of incoming data. December pricing remains at 28bp, leaving scope for further adjustment... Today’s home sales data are unlikely to matter, but tomorrow’s PPI will. That may be the catalyst for another USD leg higher."
Do Fed credibility and safe-haven inflows counter US Dollar debasement fears? Rabobank's case
Confidence in the Greenback has recovered as fears of political interference at the Federal Reserve have receded and safe-haven inflows have held up, according to the FX Strategy team at Rabobank. In the team's view, this leaves the currency better placed to benefit from strong US economic growth and forthcoming pressures in the Eurozone. Rabobank nevertheless cautions that a US budget deficit exceeding 6% of GDP, together with indications of eroding "exorbitant privilege" in the Treasury market, could put pressure on the USD over the medium term. Even so, its assessment is that earlier fears of US Dollar debasement were exaggerated.
"Diminished fears about political interference on the Fed is a supportive factor for the USD. In addition, at the start of the Gulf war, strong demand for the USD undermined last year’s claims that the USD’s had lost at least part of its safe haven value. In our view the USD’s safe haven appeal is linked to its embedded position in global payments systems, which could take decades to shake... Reduced concerns over the credibility of the greenback should allow it more opportunity to benefit from the US’s robust economic growth performance... There is still a risk that concerns related to the US’s unwieldly budget deficit could weigh on the USD over the medium-term. The US budget deficit at over 6% of GDP is wider than that of France... Either way, last year’s dollar debasement fears appear exaggerated."
What Underpins the Dollar's Strength?
Front-end interest rate repricing, confidence in institutions and structural safe-haven demand have combined to lift the US Dollar to a new year-to-date peak of 103.08. In the assessments of MUFG and ING, persistent inflation and hawkish Fed remarks, including 28 bps to 43 bps of tightening priced across December and January, together with discussion of a possible 50 bp increase, keep near-term risks tilted towards further US Dollar strength around the forthcoming PPI release. Meanwhile, Rabobank stresses that, despite medium-term fiscal deficit risks above 6% of GDP, the Greenback's deeply established position in global financial markets leaves it well placed to outperform major peers.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
POPULAR ARTICLES
1USD/CAD Price Forecast: RSI near 66 signals strong buying interest2Can the US Dollar Index Extend Gains After Hitting a Fresh Year-to-Date High of 103.08 as Fed Rate Hike Bets Rise?3New Zealand Dollar holds near 0.5550 amid a pause by US Dollar bulls4US Dollar: Rally loses steam with Fed commentary in focus – BBH5Reuters poll: Economists agree ECB will raise rates to 2.75% in December6Top Altcoins Price Forecast: What next for Ripple, Cardano and Solana as declines pause amid exhaustion signals?7British Pound: Why do resilient data bolster the case for BoE hikes? – BBH8Can Official Warnings Against Rapid Currency Moves Sustain the Japanese Yen’s Relief?9EUR/GBP Price Forecast: Can the pair sustain consolidation above 0.8350 after rejection at 0.8370?

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved