

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
As the Japanese Yen slips towards 160.00, why are strategists still betting on it to strengthen?
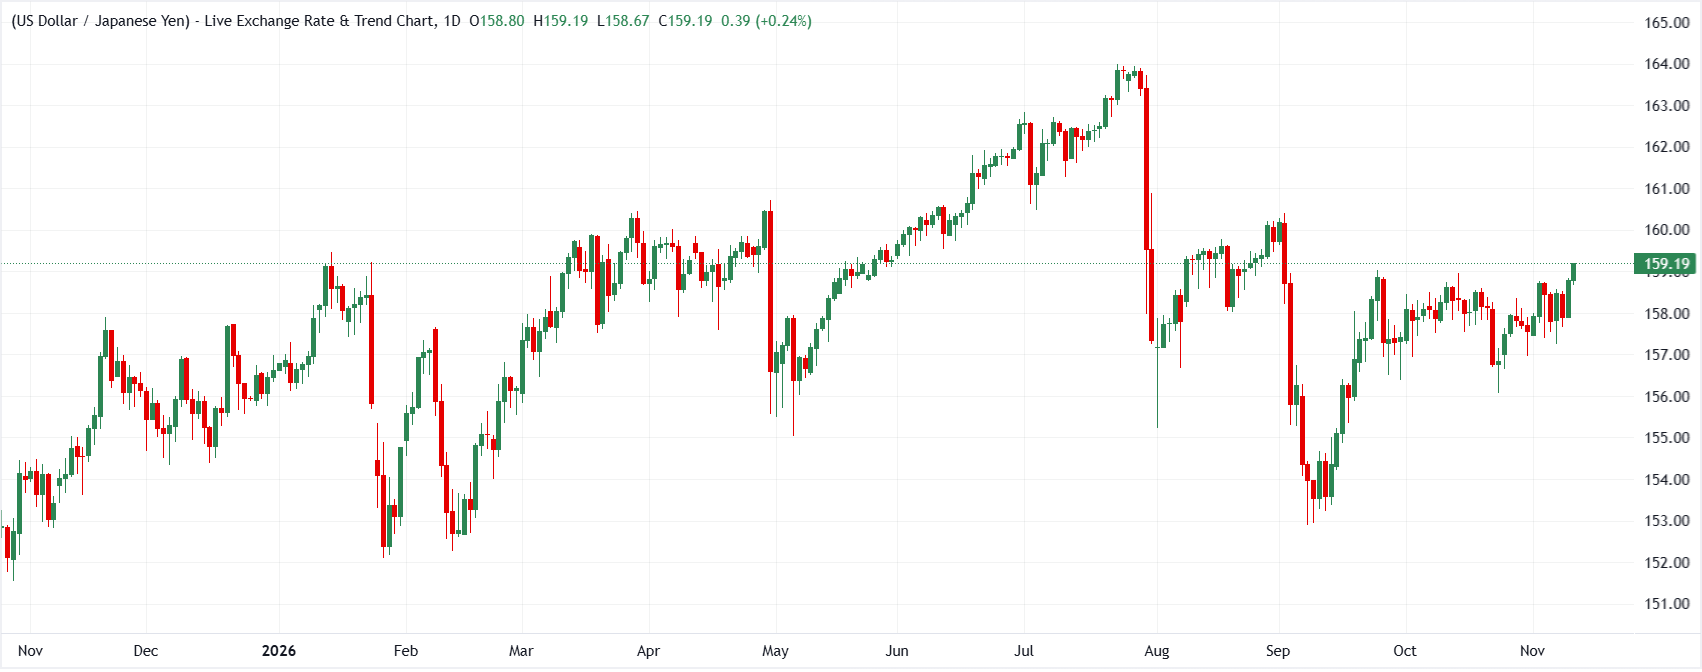
Sentiment towards the Japanese Yen (JPY) points to a possible medium-term structural recovery, with investors increasingly focused on Bank of Japan (BoJ) policy normalisation, resilience in the domestic economy and greater currency intervention risks near the 160.00 threshold. The release of US Consumer Price Index (CPI) inflation data briefly sent USD/JPY back towards the key resistance zone of 159.00–160.00. However, robust Japanese manufacturing sentiment, sustained wage growth and growing demand for Japanese Government Bonds (JGBs) are reinforcing expectations that BoJ interest rates are moving towards neutral. Strategists at ING and MUFG see rising domestic yields and the threat of official intervention making the Yen increasingly appealing at prevailing levels, even as near-term US Dollar (USD) strength tests the upside in USD/JPY.
Can stronger Japanese data and stable 2% inflation clear the way for BoJ tightening? ING’s view
Solid corporate earnings, higher wages and AI-led demand for data centres are supporting an improvement in manufacturing sentiment, according to Chris Turner at ING. These developments reinforce the Bank of Japan’s assessment that inflation is sustainably anchored at 2.00%. Turner expects broad US Dollar strength could briefly bring technical resistance at 159.00 into play, but believes a rise beyond 160.00 would draw aggressive investor buying of cheap Yen.
"All of the above can feed into the Bank of Japan's view that inflation is now stable at 2.00% and its accommodative monetary policy can be reined in... The broadly strong dollar means that USD/JPY could easily push through resistance at 159, but we increasingly think investors will be looking to acquire cheap yen should USD/JPY push above 160 again."
Can JGB inflows and a BoJ nearing neutral support medium-term Yen gains? MUFG’s assessment
Despite US inflation figures sending USD/JPY back towards 160.00, Derek Halpenny at MUFG sees the medium-term balance of risks tilted firmly towards Yen appreciation, given the prospect of official intervention and strengthening sentiment in the JGB market. A BoJ approaching its neutral rate, alongside potential tax incentives to support domestic bond buying, gives Halpenny a compelling basis for expecting a sustained recovery in the Yen.
"The yen weakened sharply yesterday in response to the US inflation data and USD/JPY has returned closer to the 160-level, above which intervention becomes a much greater prospect... There continue to be signs that confidence in the JGB market has improved, no doubt helped by the more active BoJ and the general consensus that within one or two hikes, the BoJ would be at the neutral policy rate... There is also growing speculation that the government will soon make changes to incentivise JGB buying by including individual JGB holdings in tax-free NISA accounts and/or removing these holdings from inheritance tax... With intervention likely halting the prospects to the upside, and confidence in the BoJ improving, the risks certainly look more skewed to yen strength over the medium term."
Is the Yen nearing a turning point?
Domestic monetary normalisation and stronger JGB demand are starting to offset external yield pressures, bringing the Japanese Yen closer to a crucial turning point. ING cautions that near-term USD momentum could take USD/JPY towards 159.00. Nevertheless, ING and MUFG both see scope for a medium-term Yen recovery, supported by the threat of official intervention above 160.00 and a Bank of Japan only 1–2 rate hikes away from its neutral rate.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
POPULAR ARTICLES
1Will UK inflation rise in October as Deutsche Bank expects?2US Dollar: Support Holds Firm on US Data – Societe Generale3Canadian Dollar falls to four-week lows at 1.4230 as bets on Fed tightening strengthen the Greenback4As the Japanese Yen slips towards 160.00, why are strategists still betting on it to strengthen?5US inflation fuels Fed hike bets, driving Japanese Yen lower towards 1606WTI Oil holds above $85 as optimism over a Middle East peace agreement begins to wane7EUR/USD: Pair stays range-bound amid Dollar outperformance – Societe Generale8Is the United States Dollar Index extending its rally on stronger prospects of a 50 bps Fed rate hike?9Ripple Price Forecast: XRP recovery potential remains constrained despite pause in correction


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved