

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
50 bps Fed rate hike prospects strengthen as United States Dollar Index rallies further
- 102.52 is within reach as the US Dollar Index surges. The probability of a Fed 50 bps December rate rise is gaining traction.
- Ahead of the US CPI release, the Fed’s Waller warned that higher or unchanged core readings could fuel concerns over a 50 bps policy rate hike.
- 0.3% MoM growth in October US core CPI exceeded the 0.2% forecast.
December’s Federal Reserve (Fed) policy meeting is drawing expectations of a larger interest rate increase. Against that backdrop, the US Dollar (USD) leads its major currency counterparts on Wednesday.
102.52 is the approximate level of the US Dollar Index (DXY) at the time of writing, up 0.3%. The index, which measures the Greenback against six major currencies, is at its strongest in almost four weeks.
US Dollar: Today’s Currency Performance
Today’s percentage moves in the US Dollar (USD) against the major currencies listed appear below. Its largest gain was against the Swiss Franc.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.27% | 0.25% | 0.19% | 0.26% | -0.05% | 0.20% | 0.51% | |
| EUR | -0.27% | -0.02% | -0.09% | -0.03% | -0.33% | -0.06% | 0.24% | |
| GBP | -0.25% | 0.02% | -0.06% | 0.00% | -0.31% | -0.06% | 0.26% | |
| JPY | -0.19% | 0.09% | 0.06% | 0.06% | -0.24% | 0.00% | 0.32% | |
| CAD | -0.26% | 0.03% | -0.00% | -0.06% | -0.30% | -0.06% | 0.26% | |
| AUD | 0.05% | 0.33% | 0.31% | 0.24% | 0.30% | 0.26% | 0.56% | |
| NZD | -0.20% | 0.06% | 0.06% | -0.00% | 0.06% | -0.26% | 0.32% | |
| CHF | -0.51% | -0.24% | -0.26% | -0.32% | -0.26% | -0.56% | -0.32% |
Percentage movements between major currencies are displayed in the heat map. Select the base currency in the left-hand column and the quote currency in the top row. Selecting the US Dollar on the left and following its row across to the Japanese Yen, for instance, gives the percentage change for USD (base)/JPY (quote).
50bp Fed Hike Risk: Waller Drives Market Repricing
Waller’s remarks, rather than the inflation release itself, underpin the market’s reassessment, according to MUFG analysts. They describe the rethink as “to consider the prospect of a 50bp hike,” emphasising that it is “only now being considered because of Waller’s comments prior to the CPI report rather than the CPI report itself.” In their assessment, “Waller’s comment that a stronger CPI print may warrant a 50bp hike has sparked a debate over whether Waller had knowledge of the CPI print,” contributing to higher front-end yields and a repricing of Fed expectations.
MUFG reports that “the OIS market is now partially pricing the risk of a 50bp hike on 9th December,” following Waller’s argument that “the sticky inflation and energy risks warrant the reversal of the 75bps of cuts and hence why wait two meetings to do that.”
A larger increase should not yet be treated as the base case, the bank cautions. Its analysts write: “We remain sceptical of the need to hike by 50bps at this stage and suspect the majority will see the better risk-reward in going by 25bps,” adding that “we still have another payrolls report (but no further CPI prints, although it’s the day after) before the FOMC meeting.” The risk of further market positioning towards a 50bp move remains. MUFG identifies one potential trigger: “a strong print plus a rebound in crude oil after the recent sharp drop would be one scenario of a possible more aggressive hike,” according to the bank.
Tuesday’s Consumer Price Index (CPI) release put October headline inflation at 0.4% Month-on-Month (MoM), a faster pace than the 0.3% forecast. Core CPI, which strips out volatile food and energy components, rose 0.3% over the same period, exceeding expectations of 0.2%.
102.52: US Dollar Index Holds Bullish Technical Bias
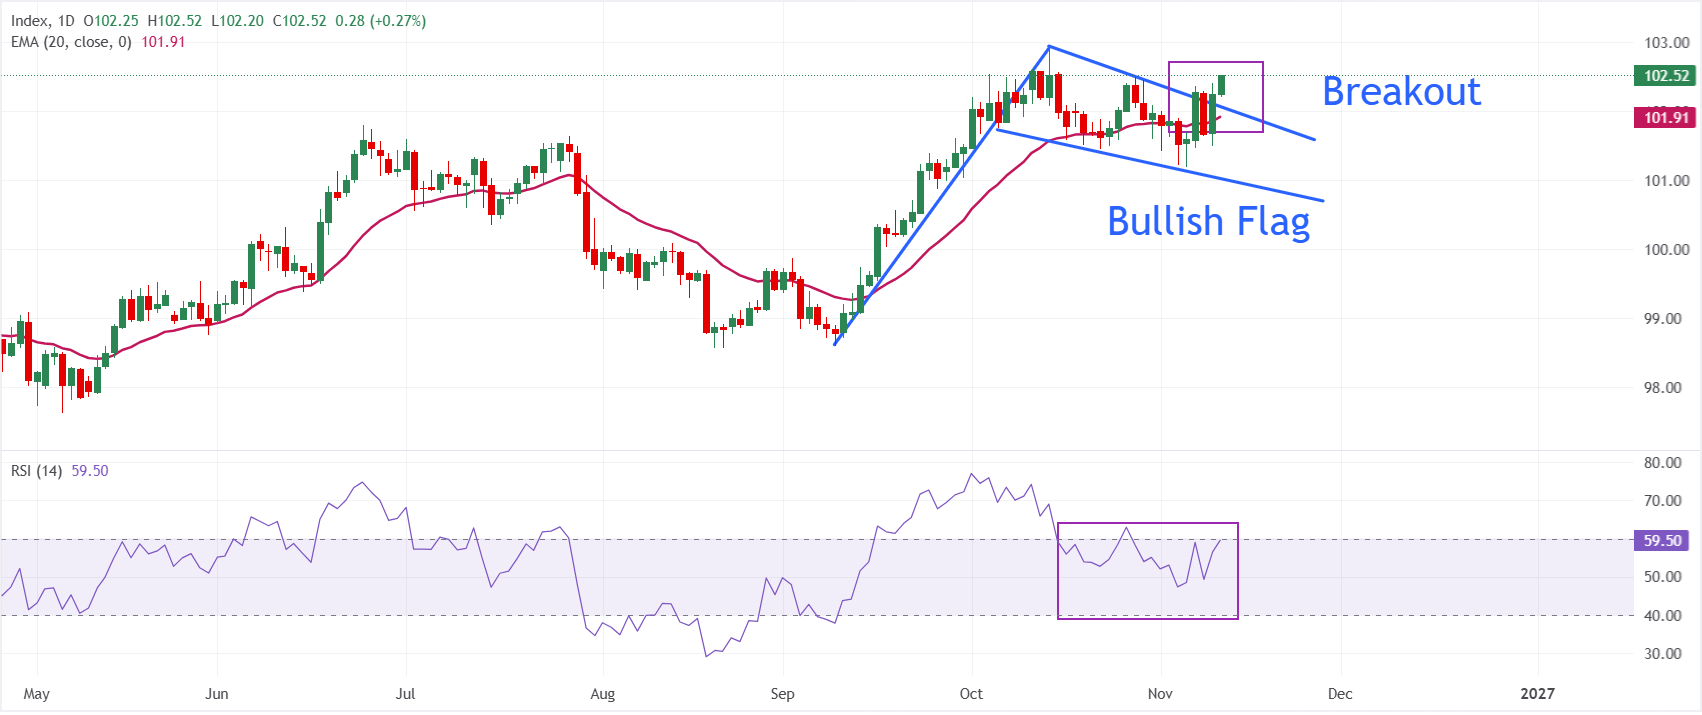
At 102.52 on the daily chart, US Dollar Index Spot retains a bullish bias. It continues to hold above the 20-day Exponential Moving Average (EMA) at 101.91, supported by a breakout from the Bullish Flag pattern.
Near 59, the Relative Strength Index (RSI) indicates a moderately positive backdrop, rather than overbought conditions.
The 102.50 region provides immediate downside support, while the EMA 20 at 101.91 adds support to underlying demand. Above the market, the descending trend barrier near 102.94 marks the main clear resistance. Closing above it on a daily basis would reinforce the bullish outlook and create scope for a stronger continuation of the recent rally.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
US Dollar: Key Questions Answered
As the official currency of the United States of America, the US Dollar (USD) also circulates alongside local banknotes as the ‘de facto’ currency in a substantial number of other countries. No currency is traded more widely. Data from 2022 show that it represents over 88% of global foreign exchange turnover, equivalent to average daily transactions of $6.6 trillion. The USD replaced the British Pound as the world’s reserve currency after the Second World War. Gold backed the US Dollar for most of its history, until the Bretton Woods Agreement in 1971 brought the Gold Standard to an end.
Monetary policy set by the Federal Reserve (Fed) is the single largest influence on the US Dollar’s value. Price stability, meaning control of inflation, and full employment form the Fed’s dual mandate. Interest rate adjustments are its main means of pursuing these objectives. If inflation exceeds the Fed’s 2% target and prices rise too rapidly, the central bank raises rates, supporting the USD. Conversely, inflation below 2% or an excessively high Unemployment Rate may prompt rate cuts, putting pressure on the Greenback.
Printing additional Dollars and introducing quantitative easing (QE) are also options available to the Federal Reserve in extreme circumstances. Through QE, the Fed sharply expands credit flows in a stalled financial system. This unconventional policy addresses a shortage of credit when banks refuse to lend to one another for fear of counterparty default. It serves as a last resort if interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, the Fed chose QE to tackle the credit crunch. The process entails printing more Dollars to purchase US government bonds, mainly from financial institutions. The US Dollar typically weakens as a result of QE.
By contrast, quantitative tightening (QT) reverses this process: the Federal Reserve ceases bond purchases from financial institutions and allows its bond holdings to mature without reinvesting the principal in further purchases. This generally supports the US Dollar.
POPULAR ARTICLES
1160.00 in sight: Why are strategists backing Japanese Yen strength despite its slide?2160 in sight: Japanese Yen weakens as US inflation fuels Fed hike bets3Above $85: WTI Oil holds steady as hopes for a Middle East peace deal begin to fade4EUR/USD: Dollar outperformance leaves pair rangebound – Societe Generale550 bps Fed rate hike prospects strengthen as United States Dollar Index rallies further6XRP Correction Pauses: Ripple Price Forecast Points to Limited Recovery Potential7US Dollar: Upside risks rise as rate hike expectations are repriced – MUFG8US Treasuries: Yields surge after CPI shock – Deutsche Bank9$4,050 ceiling keeps XAU/USD bulls in check: Gold Price Forecast


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved