

US Dollar slips against the Japanese Yen before the Bank of Japan raises rates
- USD/JPY slips to 156.00 with a Bank of Japan increase priced at 100%.
- Japan's target measure of inflation is running below 2% into the decision.
- Tokyo is shut from Monday to Wednesday for the first Silver Week since 2015.
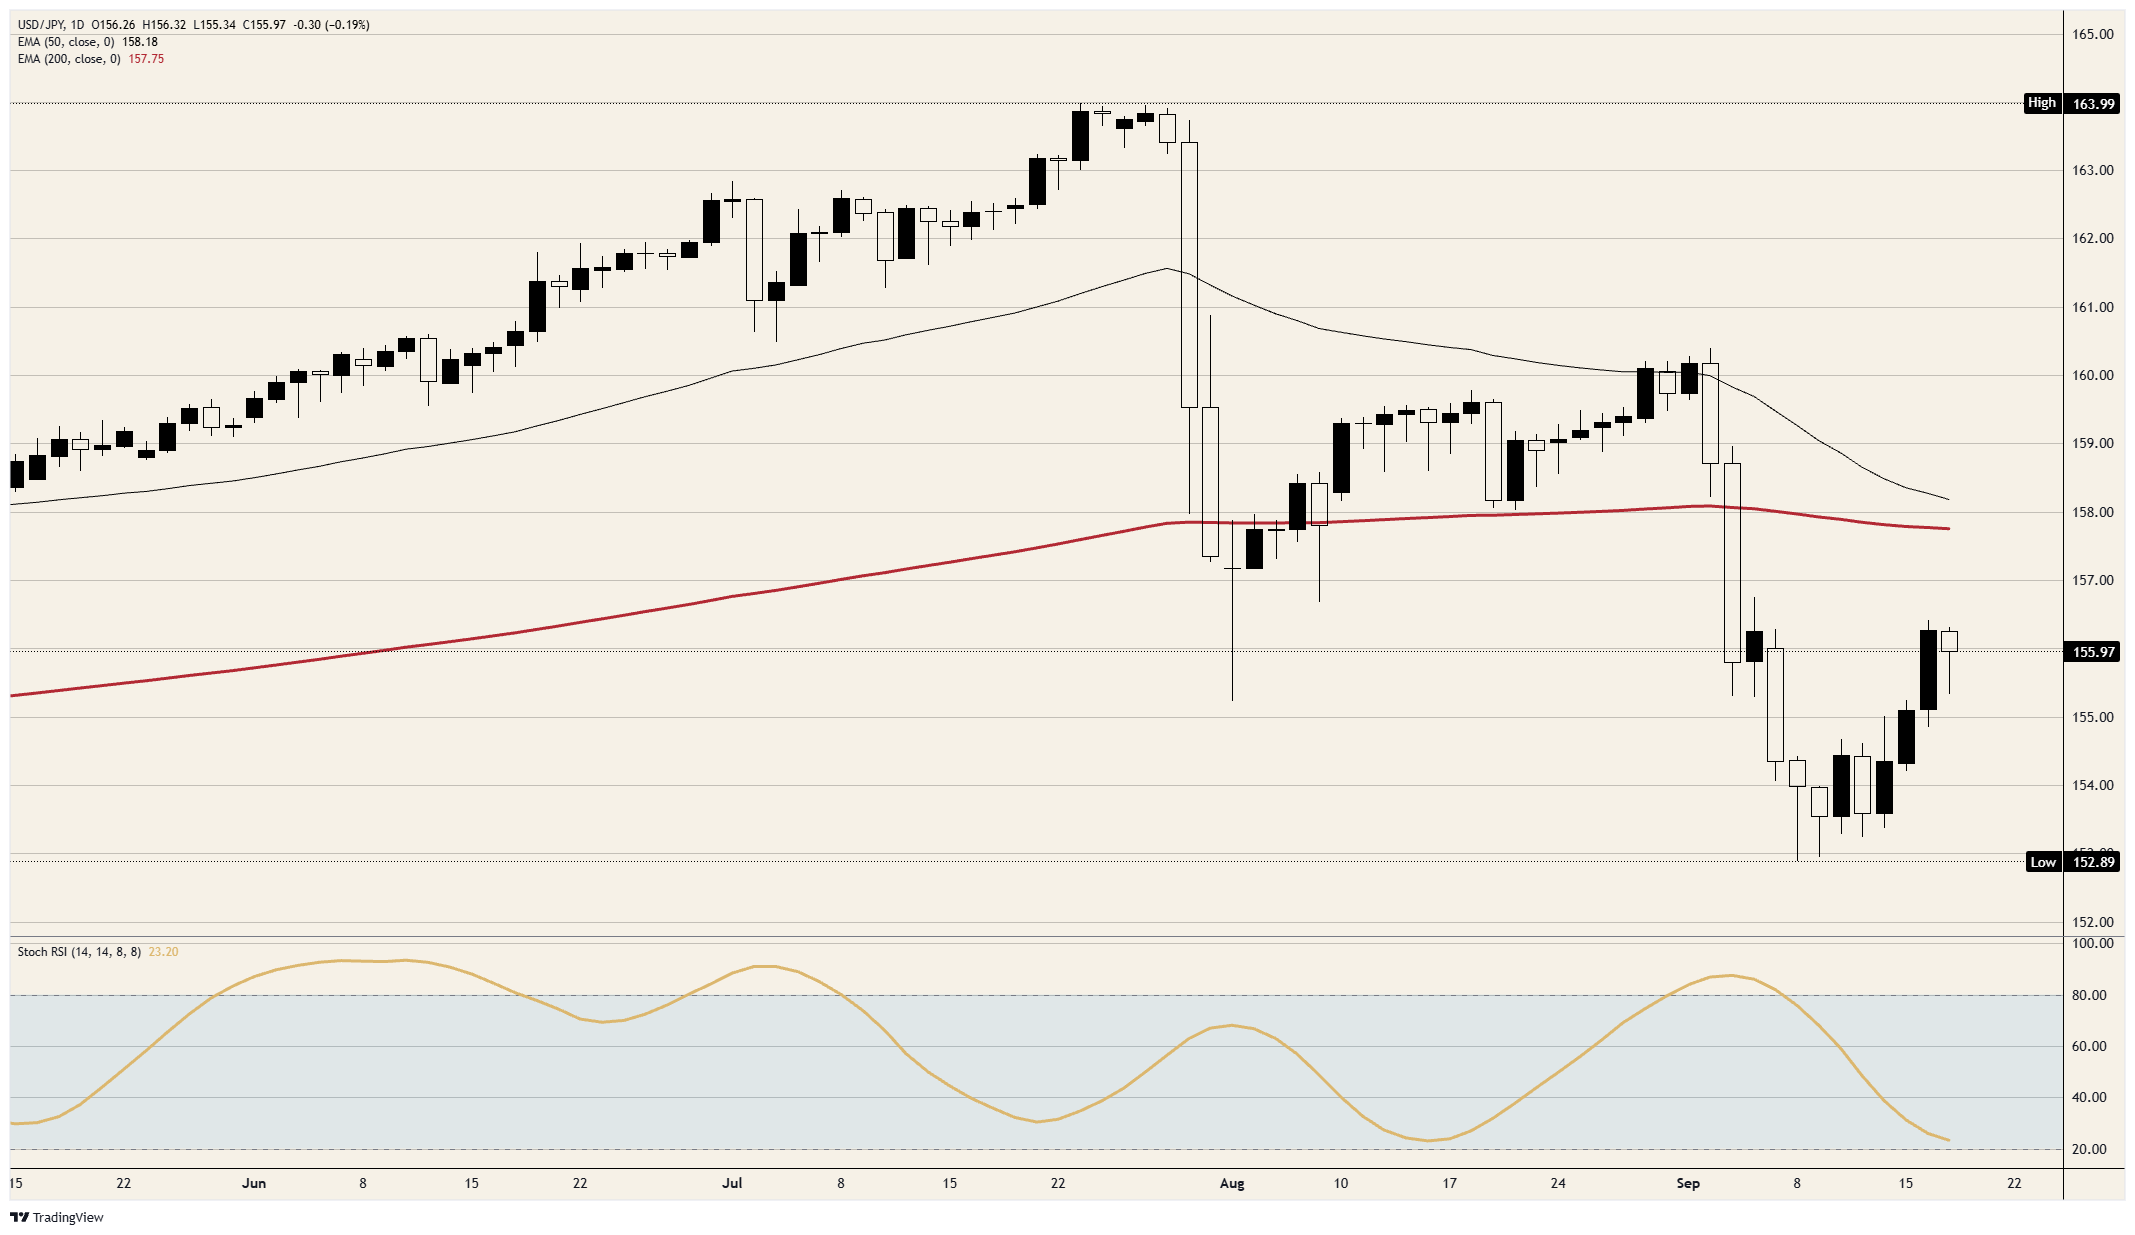
USD/JPY trades near 156.00 after a session high at 156.32 and a low at 155.34, which leaves it three Yen above the September 8 low and four below the September 2 high. The Bank of Japan announces at 02:45 GMT on Friday and a quarter-point increase to 1.25% is priced at 100%. The measure of inflation the Bank actually targets is below the target.
The increase is not about the price of anything
Japan's consumer price index excluding fresh food, the series the Bank aims at 2%, is forecast at 1.8% when the August figures arrive at 23:30 GMT, unchanged from July. The Bank's own outlook has underlying inflation accelerating clearly above 2% later in this fiscal year on wage pass-through, the oil price and a weak currency. The increase is arriving ahead of the inflation it is aimed at.
The pricing carries a little more than a quarter-point, at 0.268 of a percentage point for a move that is normally 0.25, so a fraction of the market is positioned for something larger. Japanese exports rose more than expected in August on demand for chips used in artificial intelligence, which is the corner of the economy a firmer currency reaches first.
What it is arriving behind is the intervention. Between July 30 and August 26 the Ministry of Finance spent a record 15.4 trillion Yen buying its own currency, with the United States taking part. That bought the Yen back from 164 to the middle of the 150s and no further. Reserves are finite and every operation has to be repeated the moment the selling resumes, which is the position Tokyo has been in since late July. A policy rate is the other instrument available, and unlike a reserve account it cannot be exhausted.
A year of tightening at both ends barely moves the gap
The midpoint of the Federal Reserve's band is 3.875% after Wednesday and the Bank of Japan's rate is 1%, a difference of 2.875%. Over the next twelve months the market prices the Bank of Japan up 1.03 points and the Federal Reserve up 0.72. Do the subtraction and a year of tightening at both ends narrows that difference by about a third of a percentage point.
That is the arithmetic behind a pair that has recovered three Yen from its September low rather than breaking through it. It is also why the Ministry of Finance keeps having to buy Yen: a rate of 2.03% in a year, which is what the market prices for Japan, is still nowhere near the 4.60% it prices for the United States. Friday closes a quarter of that distance and leaves the rest.
The market does not expect the next one quickly either. The October 29 meeting carries 25% odds of a further increase and December 17 carries 65%, so the path that matters starts after the holidays rather than at them. That is a lot of waiting for a currency whose last two rallies came from purchases rather than from policy.
Friday, and then nobody in Tokyo
The statement lands at 03:00 GMT and Governor Ueda takes questions at 06:30 GMT. With the decision itself fully priced, the guidance is the entire event, and the same pricing has the rate at 1.49% by December and 2.03% by this time next year. Washington adds a 07:30 GMT speech from Fed Governor Bowman and the August industrial output figures five hours after that. Neither moves this pair unless Tokyo has moved it first, and all of Friday's American session is a footnote to a Japanese overnight one.
Then Japan shuts. Monday, Tuesday and Wednesday are all holidays in Tokyo, the first five-day Silver Week since 2015, and the market does not reopen until Thursday. Thin books in the Yen are where the Ministry of Finance has done its most effective work before, and the decision lands on the last working day in Tokyo before that window opens. The American calendar fills the hole with flash purchasing surveys at 13:45 GMT on Wednesday, jobless claims on Thursday, and durable goods orders with the Michigan sentiment survey on Friday.
Levels and bias
Resistance: 156.50 has capped the bounce, with Wednesday's 156.42 the best level since the fall. The 200-day average near 157.75 is the next one, and neither has been reached since September 3.
Support: The session low at 155.34 comes first, then 155.00, which held Wednesday's low at 155.02. Beneath that, 154.00 and then the September 8 low at 152.89.
Bias: Lower while 156.50 caps. The objectives are 155.00 and then 154.00. The daily Stochastic Relative Strength Index (Stoch RSI), a momentum gauge, is near 23 and turning down again after a bounce, which fits a pair still working lower. A daily close above 157.00 ends the case.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.














