

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Gold faces pressure near $4,050 as bets on Fed rate hikes gather momentum
- Expectations of further Fed rate hikes dampen sentiment towards Gold, which has stabilised but is finding little upward momentum.
- A December Fed rate increase is fully priced into markets, while a larger 50 bps hike remains a possibility.
- The near-term technical bias remains bearish for XAU/USD as the pair struggles to recover above its 21-day SMA.
Gold (XAU/USD) is finding its footing on Wednesday, trading around $4,050 at the time of writing, a gain of 0.47% for the day. The recovery follows a 2.67% decline the previous day, when stronger-than-forecast US consumer inflation and hawkish comments from Federal Reserve (Fed) officials reinforced expectations of a more aggressive path of interest rate hikes.
October’s US Consumer Price Index (CPI) increased 0.4% MoM, exceeding the 0.3% forecast, although the pace moderated from September’s 0.6%. Excluding food and energy, core CPI advanced 0.3%, unchanged from September’s rate and above expectations of 0.2%.
Commerzbank economists warn that “prices are still rising too quickly, even though the increase was somewhat smaller than in September.” They also emphasise that “core inflation, a key gauge of the underlying trend, thus remains (too) high and is no longer trending downward,” adding that, in their view, “the strong economy and the ongoing conflict in the Middle East suggest that inflation is unlikely to ease in the near term.”
Could hawkish Fed signals pave the way for a 50 bps hike?
A half-point rate increase in December may be necessary if October core CPI registers “around 0.3% or higher.” That was the message from Fed Governor Christopher Waller ahead of the data release. As inflation reached that threshold, traders began factoring in the possibility of a larger increase at the December meeting.
Support for additional monetary tightening also came from other Fed officials, including Dallas Fed President Lorie Logan and Philadelphia Fed President Anna Paulson. Fed Vice Chair for Supervision Michelle Bowman, meanwhile, emphasised the importance of bringing inflation under control.
According to the CME FedWatch Tool, a December Fed rate hike is now fully priced in, with markets assigning an 88.5% probability to a 25-basis-point (bps) increase and an 11.5% probability to a 50 bps rise. Expectations extend to further tightening next year: traders have priced in three additional quarter-point hikes by mid-2027.
How are further rate-hike expectations lifting the US Dollar and Treasury yields?
Demand for the US Dollar (USD) strengthened as rate expectations shifted, while US government bonds suffered a sharp sell-off, led by the short end of the yield curve. On Tuesday, the policy-sensitive 2-year Treasury yield surged around 19 bps. The benchmark 10-year yield, meanwhile, rose roughly 14 bps over the day and briefly crossed back above 5%.
With Veterans Day being observed on Wednesday, the US bond market is shut. The Greenback, however, continues to advance: the US Dollar Index (DXY) is trading near 102.50, moving towards its year-to-date peak of 102.94 set in October.
Near-term pressure on Gold is likely to persist as the US Dollar strengthens, Treasury yields remain elevated and expectations of additional Fed tightening build. Over the longer term, however, strong central bank purchases and continuing inflows into Gold-backed exchange-traded funds (ETFs) could still underpin a structural floor for prices.
Technical Analysis: Can Gold regain key daily SMAs as bears maintain their grip?
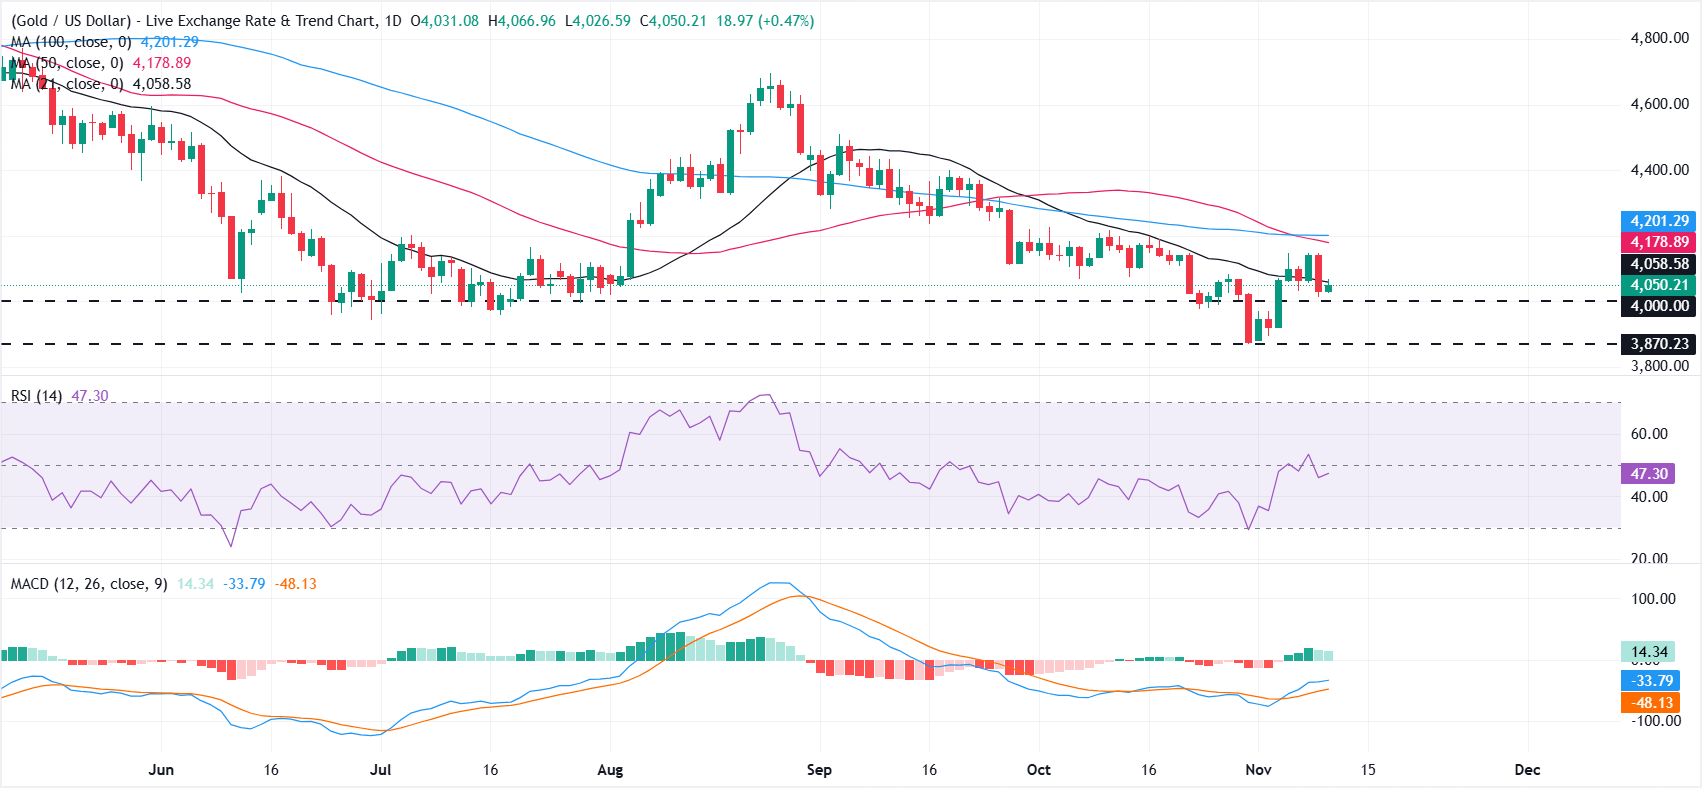
Trading below the 21-day Simple Moving Average (SMA) at $4,058, alongside the 50-day and 100-day SMAs, leaves XAU/USD with a bearish daily-chart bias. Momentum readings are mixed: the Relative Strength Index (RSI), near 47, signals neutral momentum, while the Moving Average Convergence Divergence (MACD) holds above zero. Nevertheless, shrinking green histogram bars point to a loss of bullish momentum.
The first hurdle for a recovery is the 21-day SMA around $4,058. Beyond it, resistance lies at the 50-day SMA of $4,178 and the 100-day SMA of $4,201, where sellers are likely to protect the recent range highs. Immediate support is provided by the psychological $4,000 mark, ahead of the yearly trough at $3,870.23. A clear break beneath that low could leave Gold vulnerable to additional selling pressure.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Gold: frequently asked questions
Widely used both to preserve value and to facilitate exchange, Gold has occupied an important place throughout human history. Beyond its lustre and use in jewellery, the precious metal is now commonly regarded as a safe-haven asset, or an attractive investment during periods of turmoil. It is also widely considered a hedge against inflation and currency depreciation, since it does not depend on a particular issuer or government.
The largest holders of Gold are central banks. To support their currencies during unsettled periods, they typically diversify reserves and purchase Gold, reinforcing perceptions of economic and currency strength. Substantial Gold holdings can bolster confidence in a country’s solvency. World Gold Council data show that central banks expanded their reserves by 1,136 tonnes of Gold, valued at around $70 billion, in 2022. No larger annual purchase has been recorded since records began. Emerging-economy central banks, including those in China, India and Turkey, are rapidly building up their Gold reserves.
Both the US Dollar and US Treasuries, major reserve and safe-haven assets, have an inverse correlation with Gold. A weaker Dollar typically accompanies a rise in Gold, allowing investors and central banks to diversify their holdings during turbulent periods. The metal also tends to move inversely to risk assets: stock-market rallies generally weigh on Gold prices, whereas selling in riskier markets usually supports the precious metal.
A broad set of influences can drive Gold prices. Its safe-haven appeal means geopolitical instability or concerns about a deep recession can rapidly lift prices. Because Gold offers no yield, lower interest rates tend to support it, while a higher cost of borrowing usually weighs on the yellow metal. Most price movements, however, hinge on the US Dollar (USD), as Gold is quoted in dollars (XAU/USD). Dollar strength generally restrains Gold prices; a weaker Dollar, by contrast, is likely to lift them.
POPULAR ARTICLES
1EUR/USD: Range persists as Dollar outperforms – Societe Generale2Is the United States Dollar Index extending its rally on stronger prospects of a 50 bps Fed rate hike?3Ripple Price Forecast: XRP recovery potential remains constrained despite pause in correction4US Dollar: Why Rate Hike Repricing Is Raising Upside Risks – MUFG5US Treasuries: How did the CPI shock drive yields sharply higher? – Deutsche Bank6Gold Price Forecast: Can XAU/USD extend gains with bulls held below $4,050?7Gold faces pressure near $4,050 as bets on Fed rate hikes gather momentum8EUR/USD Price Forecast: Fresh decline below 1.1100 gathers support from a stronger US Dollar9Why Does Societe Generale See the Australian Dollar as Vulnerable After Weak Data?

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved