

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
December rate hike expected from Bank of Japan: Why is the Japanese Yen still weakening?
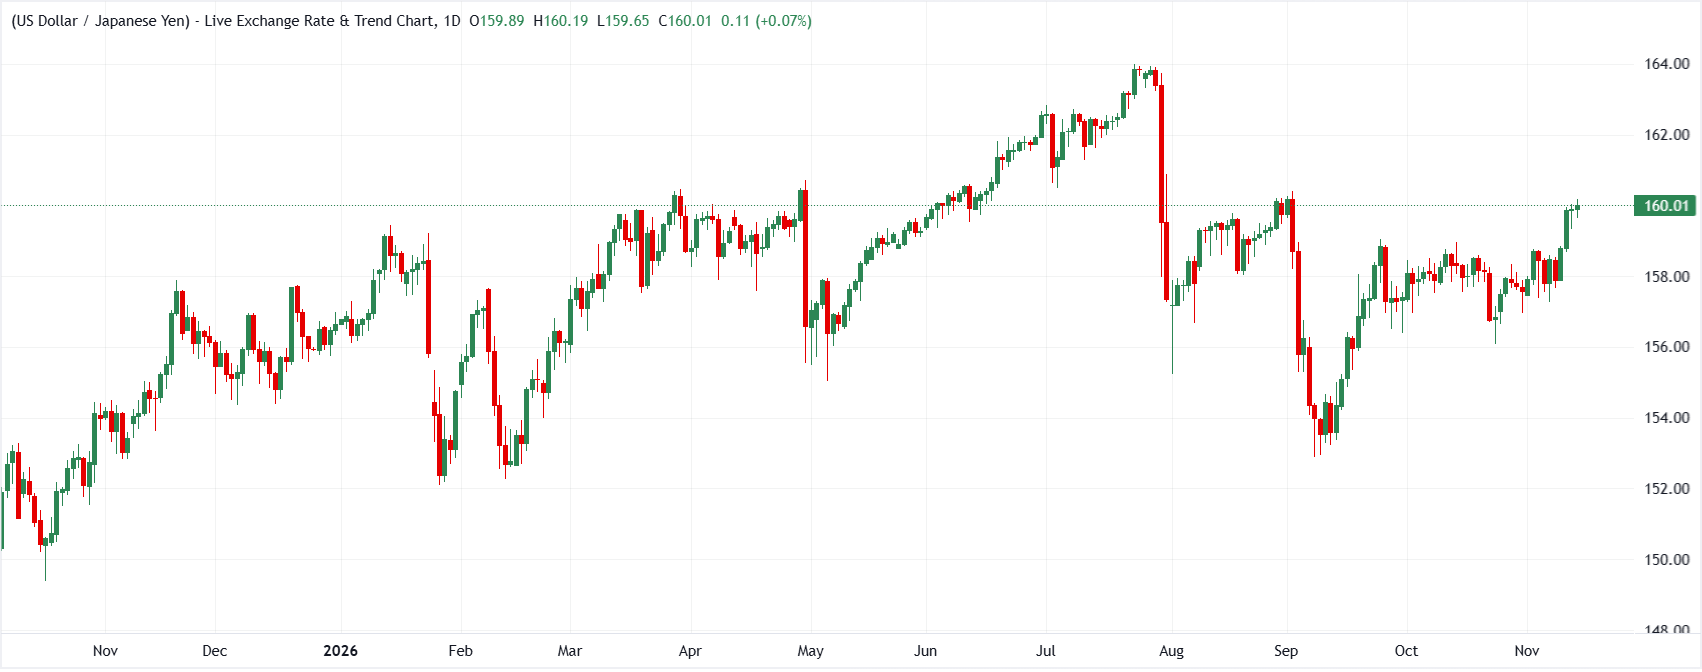
Pressure persists on the Japanese Yen (JPY) as USD/JPY trades above 160.00. The pair has exceeded that level for a second consecutive session, leaving the Yen near multi-month lows and drawing warnings from Japanese Finance Minister Katayama over one-sided, rapid foreign exchange moves. Japan’s resilient domestic activity — with Q3 real GDP growth projected at 0.8% QoQ saar — and above-target inflation support expectations of a 25 bps Bank of Japan (BoJ) rate increase in December. However, higher expectations for Federal Reserve (Fed) tightening are offsetting that domestic policy support. Strategists at DBS Group Research, Societe Generale, and Commerzbank are weighing two possibilities: whether technical breakouts above 160.00 will prolong near-term Yen losses towards 162.20, or whether changes in Japan’s interest rate environment will underpin a longer-term JPY recovery.
25 bps December BoJ hike warranted by firm growth and above-target inflation, DBS expects
Japan’s third-quarter real GDP growth is forecast at 0.8% QoQ saar by economists at DBS Group Research. AI-related export demand and wage-supported domestic consumption are expected to drive the expansion. October’s trade deficit is projected to widen to JPY1.2 trillion even as exports grow 17% YoY. Nevertheless, inflation remaining above target, fuelled by higher energy costs and Yen weakness, should strengthen the argument for a 25 bps Bank of Japan rate increase in December.
"Real GDP is expected to expand by 0.8% qoq saar in 3Q, broadly in line with trend... October trade data are likely to show export growth remaining solid at 17% yoy, but the trade deficit widening to JPY1.2tn... Overall, these data should reinforce the case for a 25bp BOJ rate hike at the December policy meeting, with growth around trend, inflation above target, and continued pressure on external balance/exchange rate."
160 break puts USD/JPY on course for possible 162.20 test, Societe Generale warns
A move above its tight consolidation range has also taken USD/JPY back above its 200-day moving average, according to Kenneth Broux and colleagues at Societe Generale. The pair traded above 160.00 for a second consecutive day, although verbal warnings from Finance Minister Katayama subsequently curbed its advance. Initial support lies at the 200-day SMA around 158.70. A sustained rise would leave the Japanese Yen vulnerable as USD/JPY approaches key resistance at 160.40/160.70 and 162.20.
"USD/JPY witnessed a sharp rebound in September and evolved within a narrow consolidation. It has now broken out above the upper limit of this rang denoting possibility of extension in bounce. The next potential hurdles could be located at April high of 160.40/160.70 and projections near 162.20... The pair has reclaimed the 200-DMA. If a short-term pullback develops, the moving average at 158.70 could be an important support... USD/JPY: 159.66 - 160.19 overnight range. Spot trades through 160 for second day before traders pare back on warning by FinMin Katayama one-sided action and rapid forex moves. Support 158.70, resistance 160.70."
155.00 by mid-2027: Commerzbank sees Fed-BoJ convergence limiting Yen gains before structural recovery
An additional Federal Reserve rate increase is now expected in March, offsetting the currency benefit of anticipated Bank of Japan hikes in December and next spring, argues Volkmar Baur at Commerzbank. With both central banks signalling tighter policy, their paths are converging rather than diverging. Commerzbank therefore expects little near-term scope for Japanese Yen appreciation, forecasting only a modest move towards 155.00 by mid-2027. Over the longer term, however, structurally more attractive domestic bond yields are expected to underpin a sustained JPY recovery.
"This reassessment of our US central bank expectations naturally impacts our forecast for the Japanese yen as well. Our economists no longer expect the US central bank to halt its interest rate hikes in December. Instead, they have factored in a further rate rise by the Fed in March... While we also expect the Bank of Japan to implement two further rate rises - in December and in spring next year - this no longer favours the Japanese yen. Rather, it signals a convergence between the central banks, which will likely have little impact on the currency... Consequently, we see little potential for the Japanese yen in the near future. In recent days, the yen has already weakened slightly due to rising market expectations regarding the Fed, and is currently trading just below USD-JPY 160. By the middle of next year, we now expect only a slight appreciation towards 155... In the longer term, however, we continue to expect the JPY to strengthen. The structural shift in Japan’s interest rate landscape means that domestic bonds are once again significantly more attractive, particularly for Japanese investors."
160.00: stronger Japanese fundamentals meet external rate pressure
160.00 remains the focal level for the Japanese Yen. Improving domestic fundamentals are competing with continued pressure from overseas interest rates. For DBS Group Research, trend GDP growth of 0.8% QoQ saar and persistent inflation provide firm grounds for a 25 bps BoJ rate increase in December. By contrast, Societe Generale cautions that USD/JPY’s technical break above its 200-day SMA at 158.70 exposes the Yen to tests of 160.40/160.70 and 162.20, unless official intervention arrests the move. Meanwhile, Commerzbank stresses that parallel Federal Reserve tightening through March will restrict near-term JPY appreciation to around 155.00. A more lasting Yen recovery would come later, as higher Japanese bond yields draw sustained domestic capital inflows over the longer term.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
POPULAR ARTICLES
1Below $68,000: Bitcoin Weekly Forecast as BTC selling persists despite oversold signal26.5%: United States annual producer inflation rises in October, below 6.6% forecast3Mixed Eurozone data: Euro pares gains against British Pound4December rate hike expected from Bank of Japan: Why is the Japanese Yen still weakening?50.5527 in focus: NZD/USD price forecast as bears build momentum to test 19-month lows6200-day average reclaimed as Brent oil rebounds – BBH7160.00 under bullish pressure: USD/JPY Price Forecast as intervention risks mount8$20 Million in 24-Hour Liquidations: Ripple Price Forecast Puts XRP’s $1.00 Support at Risk9Below $87: WTI Oil pares gains on bets of a steeper Fed tightening cycle


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: support@tmgm.com.au
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: support@tmgm.com
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: support@tmgm.com
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: support@tmgm.com
Copyright © TMGM. All rights reserved